Indexed Universal Life Insurance (IUL) | Generis Organization
Be Your Own Bank · Protect Your Family

Life insurance that protects you
at every stage of life.

An Indexed Universal Life policy is designed to help protect your family while building long-term financial flexibility for the future. During your complimentary review, Kirt Patel, Founder of Generis Organization, will help you compare options and determine whether an IUL fits your goals, budget, and long-term plans.

Request My Complimentary Review

Complimentary review • No obligation • Personalized recommendations

Why Families Trust Generis

5.0 ★★★★★ Google & Facebook Reviews
Work Directly With Kirt Patel
Licensed Advisor • Multiple A-Rated Carriers
Complimentary Review • No Obligation

Build a personalized IUL strategy for your family, retirement, and future.

Kirt will personally review your goals, budget, and current coverage to help determine whether an IUL is the right fit. If another option makes more sense, he'll explain that instead. Every recommendation is personalized to your situation, not a generic quote.

You'll hear directly from Kirt Patel — not a call center or a group of agents. Your information is never sold.

Questions first? Call Kirt or text Kirt, email Kirt, or schedule a consultation.

Not sure if an IUL is right for you? Keep scrolling to learn how it works before requesting your complimentary review.

What Clients Say

Real Experiences. Personal Guidance.

Real reviews from clients across Google and Facebook.

★★★★★ 5.0 Client Reviews
★★★★★

“Kirtan took the time to explain all of my options clearly, without any pressure.”

Working with Kirtan Patel for my life insurance planning has been an exceptional experience. Financial planning can feel overwhelming, but Kirtan took the time to explain all of my options clearly, without any pressure. He helped me structure a plan that protects my family today while building a secure foundation for my retirement. His knowledge, patience, and professionalism gave me complete peace of mind. I highly recommend Kirtan to anyone looking for an honest, trustworthy advisor
Paula C. Reviewed on Google
★★★★★

“Kirt went above and beyond... KP would call just to check in on me even after i got things all the way str8”

All i can say when i need my life insurance Kirt went above and beyond even though it took a min to get things str8 on my end KP would call just to check in on me even after i got things all the way str8 till this day KP picks up the phone and we just talk great guy Kirt Patel so when y’all reading these reviews just know when you’re looking for great everything this is the company

Selven M. Reviewed on Google
★★★★★

“He took his time and explained things and did not pressure me into buying anything.”

Mr Kirt Patel treated me with kindness and got me the best deal he could on my life insurance. I am forever grateful because I don’t know a lot on this subject. He took his time and explained things and did not pressure me into buying anything. I believe that is one of the things I liked about him. I do not like being pressured. Thank you again Mr Patel

Tonda K. · Indiana Reviewed on Facebook
42%
of Americans say they need (or need more) life insurance.
Source: LIMRA 2024 Insurance Barometer Study
55%
of Americans worry they won't have enough money saved for retirement.
Source: Gallup Economy & Personal Finance Survey
0%
A common indexed-crediting floor; policy charges can still reduce value.
Source: Indexed Universal Life policy contracts (varies by carrier)
Tax-Advantaged
Potential access to retirement income through policy loans when structured properly.
Source: IRS Tax Code & carrier policy provisions

One policy. Three powerful benefits.

Unlike many life insurance policies that focus on a single purpose, an Indexed Universal Life policy can help protect your family today while creating financial flexibility for the future.

Death Benefit

Protect the people you love.

Your beneficiaries may generally receive an income-tax-free death benefit under current federal law, subject to individual circumstances.

  • Replace lost income
  • Help pay off debts or a mortgage
  • Cover education expenses
  • Leave a financial legacy
Cash Value

Build long-term financial flexibility.

Part of your premium builds cash value that grows tax-deferred based on index performance, subject to policy terms.

  • Tax-deferred growth potential
  • Access through policy loans
  • Supplement retirement income
  • Maintain lifelong coverage
Living Benefits

Protection while you're living.

Many IUL policies include accelerated death benefit riders that may provide access to a portion of your death benefit if you experience a qualifying illness.

  • Chronic illness protection
  • Critical illness protection
  • Terminal illness protection
  • Greater financial peace of mind

The best time to start is usually earlier.

One of the biggest advantages of Indexed Universal Life isn't just the policy itself—it's giving your policy more time to work for you. Kirt often explains that starting earlier may provide more time for coverage and cash-value accumulation, while waiting can affect cost, eligibility, and long-term policy performance.

Starting Earlier

Beginning while you're younger and healthier may provide more long-term flexibility.

  • May qualify for more favorable rates.
  • More years to build cash value.
  • More time for tax-deferred growth potential.
  • Longer period of family protection.
  • Health changes are less likely to affect eligibility.

Waiting Longer

Waiting isn't always the wrong decision, but it can reduce some of the advantages an IUL offers.

  • Premiums may be higher.
  • Fewer years for cash value accumulation.
  • Health changes could affect approval or pricing.
  • Less time to prepare for retirement goals.
  • Family remains unprotected until coverage is in place.

Every situation is different, and no one can predict the future. During your complimentary review, Kirt will help determine whether an Indexed Universal Life policy makes sense based on your age, health, financial goals, and long-term plans.

⏰ Age and health can affect IUL pricing, eligibility, and long-term policy performance.
Request a complimentary review and Kirt can show you how available options may look at your current age.

Like any financial strategy, Indexed Universal Life isn't the right solution for everyone.

Kirt's role isn't to assume an IUL is right for you—it's to help determine whether it actually fits your goals. If another type of life insurance makes more sense, he'll explain that too.

✅ An IUL May Be a Great Fit If You...

  • Want permanent life insurance that lasts your lifetime.
  • Would like the opportunity to build tax-advantaged cash value over time.
  • Want living benefits that may help during certain serious illnesses.
  • Are planning for retirement and want another source of potential tax-advantaged income.
  • Want flexibility to adjust your coverage as life changes.

❌ Another Policy May Be Better If You...

  • Only need inexpensive temporary life insurance for a short period.
  • Are looking for a short-term investment rather than long-term protection.
  • Need the absolute lowest monthly premium possible.
  • Don't want to actively fund a policy over time.
  • Simply want basic life insurance without any additional features.

Every family's situation is different. During your complimentary review, Kirt will explain your options and help identify the solution that may best fit your goals—even if it isn't an Indexed Universal Life policy.

How an Indexed Universal Life policy actually works.

An Indexed Universal Life policy combines permanent life insurance with a cash-value component. Interest may be credited using an external market index under the policy's formula, but policy value is not invested directly in that index. For the complete educational starting point, read what an IUL is and how it works.

Index-linked interest with contract limits

Interest may be credited using the performance of an external index such as the S&P 500, without directly investing policy value in that index. Floors can limit negative indexed interest, while caps, participation rates, spreads, and other provisions can limit credited gains. Policy charges can still reduce value.

Tax-deferred growth inside the policy

Interest credited inside an IUL generally accumulates tax-deferred while the policy remains in force. Tax treatment depends on current law, policy status, and individual circumstances.

Potential access through policy loans

When sufficient value is available, policy loans may provide access for needs such as a business opportunity, college tuition, or retirement income. Loans accrue interest and can reduce policy value and the death benefit, increase lapse risk, and create tax consequences if the policy lapses or is surrendered. Loan treatment varies by contract.

Increasing death benefit option

Some policies offer an increasing death-benefit option that can combine a stated insurance amount with policy value. Its availability, calculation, and cost depend on the policy, and policy values are not guaranteed to increase.

Premium flexibility

An IUL may allow premium changes within contract limits. Flexibility does not make payments optional without consequences; the policy still needs enough funding and value to support charges and remain in force.

Cost depends on the policy design

IUL, whole life, and term life use different guarantees, funding structures, and features. The appropriate cost comparison depends on the coverage amount, underwriting, funding goal, charges, and actual contracts—not a universal ranking.

Which policy best fits your goals?

Every type of life insurance has strengths. The right choice depends on what you're trying to accomplish. Here's a quick comparison to help you understand the differences.

👉 Swipe left to compare all coverage options

Feature Term Life Whole Life IUL
Family Protection ✔ Included ✔ Included ✔ Included
Lowest Cost ✔ Best Option ✖ Highest Cost ◐ Moderate Cost
Cash Value Growth ✖ No ✔ Guaranteed ✔ Growth Potential
Retirement Protection ✖ No ◐ Can Help ✔ Often Used For This
Indexed-Crediting Floor ✖ No ✔ Stable Growth ✔ Policy-Dependent
Living Benefits ◐ Optional Riders ✔ Often Included ✔ Often Included
Flexible Coverage ✖ Limited ✖ Fixed ✔ Flexible Within Limits
Often Best For... Families needing affordable temporary protection such as for a mortgage. People who prioritize guarantees and predictable growth. Families looking for lifelong protection, tax-advantaged cash value growth, and greater financial flexibility.

Family Protection

Term Life Included
Whole Life Included
IUL Included

Lowest Monthly Cost

Term Life Best Option
Whole Life Highest Cost
IUL Moderate Cost

Cash Value Growth

Term Life None
Whole Life Guaranteed
IUL Growth Potential

Retirement Protection

Term Life No
Whole Life Can Help
IUL Often Used For This

Indexed-Crediting Floor

Term Life No
Whole Life Stable Growth
IUL Policy-Dependent

Living Benefits

Term Life Optional Riders
Whole Life Optional Riders
IUL Often Included

Flexible Coverage

Term Life Limited
Whole Life Fixed
IUL Flexible Within Limits

Often Best For...

Term Life Affordable temporary protection.
Whole Life Guaranteed growth and predictable premiums.
IUL Lifelong protection, cash value growth, and long-term flexibility.

Remember: the best policy isn't the one with the most features—it's the one that best fits your family's goals, budget, and long-term plans.

During your complimentary review, Kirt will explain the pros and cons of each option and help identify the solution that may fit your goals—even if it isn't an Indexed Universal Life policy.

Every recommendation starts with your situation, not the product.

The goal isn't to convince you an IUL is right for you. The goal is to help you understand whether it is.

🔑

IUL requires an application and health review before approval.

An IUL requires an application and underwriting review before approval. Before anything is submitted, Kirt will review your situation, explain what to expect, and help make sure you understand the process and available options.

If you don't qualify for an IUL, that doesn't necessarily mean you're out of options. Kirt can help you review alternatives such as a different policy structure, whole life insurance, or term life insurance based on your age, health, goals, and budget.

Index-linked interest with policy-specific limits.

An indexed account can provide interest-crediting potential without directly investing policy value in the market. The result depends on the policy's formula, crediting terms, charges, funding, and other activity.

A Floor Can Limit Negative Indexed Interest

Many policies use a 0% floor for a stated crediting period, so a negative index result may produce 0% indexed interest rather than a negative credit. Charges, loans, and withdrawals can still reduce policy value.

Participation in Index Gains

When the measured index rises, the policy may credit part of that increase. Caps, participation rates, spreads, and other provisions determine how much is credited.

Credited Interest Follows the Contract

Interest credited at the end of a completed period is added under the policy's terms. Future index declines do not retroactively change that credit, but ongoing charges and policy activity can reduce total value.

Policy Value Is Not Directly Invested in the Index

The external index is used in a crediting formula rather than as a direct investment. That can limit direct market-loss exposure, but it does not guarantee growth or prevent poor policy outcomes.

A crediting floor applies to the indexed-interest calculation—not to the policy's total value. Review both the crediting terms and the charges shown in the contract and illustration.

Your IUL is structured for what matters most to you.

There's no one-size-fits-all IUL. Kirt can help structure a policy around your primary objective—whether that's emphasizing the death benefit, building cash value, or creating potential future retirement flexibility.

🛡️ Maximum Death Benefit

This design may fit someone whose primary goal is emphasizing the death benefit for family or business needs. Life insurance death benefits are generally received income-tax-free under current federal law, subject to individual circumstances.

  • Higher death benefit from day one
  • Still builds cash value over time
  • May include living benefits for qualifying illness
  • An increasing death benefit option may be available
  • Best for: family protection, estate planning, business buy-sell agreements

💰 Maximum Cash Value (LIRP)

This design may fit someone focused on building policy value for potential future access, sometimes described as a Life Insurance Retirement Plan (LIRP). Loans are subject to interest and policy terms and can reduce values and benefits or increase lapse and tax risk.

  • Faster cash value growth
  • More policy value targeted for potential access
  • Potential supplemental retirement income
  • May include living benefits for qualifying illness
  • Best for: retirement planning, high-income earners, maxing tax-advantaged accounts

An IUL may be worth considering if…

You're maxing out your 401k and IRA and looking for additional tax-advantaged savings

You've heard about "being your own bank" or infinite banking and want to understand if it's right for you

You're between ages 18–65 and want to lock in permanent coverage while you're healthy

You're a business owner looking for a tax-efficient way to protect yourself or fund a buy-sell agreement

Personalized guidance. Multiple insurance companies. One trusted advisor.

Buying life insurance shouldn't feel confusing or high-pressure. As an independent advisor and broker, Kirt compares options from multiple insurance companies and helps clients understand which approach may fit their family's goals.

If You Ever Need to File a Claim

Kirt remains available to help your family understand the claims process so they're not left navigating it alone during a difficult time.

Policy Reviews Over Time

Life changes. Kirt remains available for future policy reviews as your situation, goals, or coverage needs change.

Beneficiary Updates, Handled Personally

Marriage, children, and other major life changes can affect your beneficiary choices. Kirt can help you review and update them when needed.

A-Rated Insurance Companies

Generis works with established insurance companies so Kirt can compare available products instead of relying on a single carrier.

Straightforward, No-Jargon Guidance

Kirt explains policy features, tradeoffs, and illustrations in plain language so you can understand what you're considering before making a decision.

Personally Licensed in 9 States

Families across nine states trust Generis Organization for honest guidance and long-term protection.

Simple. Personalized. No pressure.

Getting an IUL structured correctly takes a real conversation — not a one-size-fits-all quote. Here's exactly what happens when you reach out.

1

You Request a Complimentary Review

Fill out the form and share your goals—family protection, cash-value growth, retirement income, or a combination. It takes less than 2 minutes to complete.

2

Kirt Prepares Your Illustration

Kirt compares available options and prepares a personalized illustration tailored to your age, budget, and goals—showing guaranteed and nonguaranteed values under stated assumptions, not promised future results.

3

You Make an Informed Decision

No pressure. Kirt will walk you through the illustration and answer your questions. If you decide to move forward, he'll help you with the application process. If not, there's no obligation.

Learn More Before You Decide

Explore Our Indexed Universal Life Insurance Guides

Want to understand your options before requesting a personalized review? Browse our educational guides covering how Indexed Universal Life Insurance works, the pros and cons of indexed universal life, IUL vs. whole life insurance, and how IUL policy loans work.

IUL Fees and Policy Charges
Learn about cost of insurance, premium loads, administrative fees, rider charges, and how policy charges can affect cash value over time.

Browse IUL Guides

Answers before you reach out

How is an IUL different from a 401(k) or Roth IRA? ▾
A 401(k) and Roth IRA have annual contribution limits. An Indexed Universal Life policy has different funding rules based on IRS guidelines and policy design. Unlike traditional retirement accounts, an IUL also provides a life insurance death benefit and may include living benefits, while offering the potential for indexed interest crediting subject to policy terms.
Is this the same as infinite banking or being your own bank? ▾
An Indexed Universal Life policy can be structured to support strategies commonly referred to as Infinite Banking or Becoming Your Own Bank. These strategies generally involve accessing policy cash value through loans, subject to policy terms and conditions. Whether this approach is appropriate depends on your financial goals and how the policy is designed.
Is the cash value really tax-free when I access it? ▾
Policy loans are generally not considered taxable income while the policy remains in force. Tax treatment depends on current tax law and individual circumstances. If a policy lapses with an outstanding loan, taxes may apply. Consult a qualified tax professional regarding your specific situation.
What happens if the market crashes? ▾
Indexed Universal Life policies credit interest based on the performance of a market index without directly investing in the market. Many policies include a 0% floor, meaning a negative index performance does not necessarily result in negative credited interest for that crediting period, subject to the policy's terms. Policy charges, loans, and withdrawals can still reduce policy value.
What if I don't qualify for an IUL? ▾
If an Indexed Universal Life policy is not the best fit or you do not qualify, other life insurance solutions such as whole life or term life insurance may be available based on your age, health, and financial goals.
How long does it take to build meaningful cash value? ▾
Indexed Universal Life insurance is generally designed as a long-term financial strategy. Cash value accumulation depends on factors such as policy design, premium funding, credited interest, expenses, and the length of time the policy remains in force.
What's the minimum to get started? ▾
Minimum face amounts and premium requirements vary by insurance company, your age, health, and how the policy is designed. During your complimentary review, you'll receive a personalized illustration based on your specific situation.
Am I obligated to buy anything after the complimentary review? ▾
No. Your complimentary review is educational and there is absolutely no obligation to purchase a policy. The goal is to help you understand your options and determine whether an Indexed Universal Life policy is appropriate for your needs.
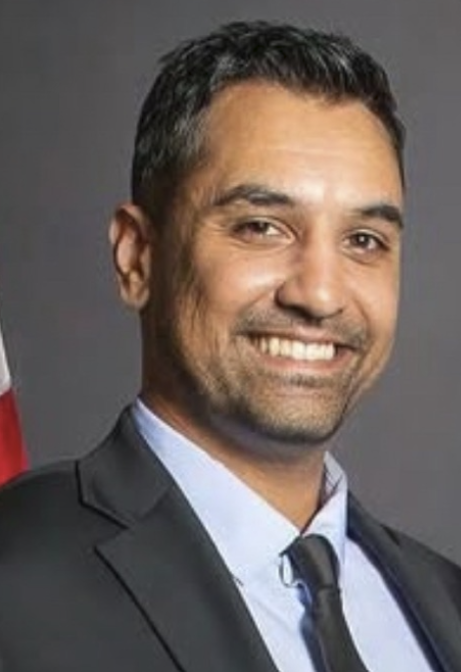
Kirt Patel

Helping Families Protect What Matters Most

Founder of Generis Organization • Independent Life Insurance Advisor

I believe life insurance should never feel confusing or high-pressure. My job is to help you understand your options, answer your questions honestly, and recommend coverage that fits your family's goals—not someone else's sales target.

As an independent advisor and broker, I compare multiple highly rated insurance companies so you're not limited to one carrier's products. Every recommendation is personalized to your goals, health, budget, and your family's needs.

My relationship with clients doesn't end once a policy is issued. Whether you need to review your coverage years later, update beneficiaries after a life change, or your family ever needs help filing a claim, I'll be here to guide you every step of the way.

My goal is simple: to give every individual and family confidence that the people they love—and the life they've worked so hard for—are protected.

Compare Coverage From Trusted Insurance Companies

Corebridge Financial
Transamerica
American Amicable
F&G

Personally Licensed Across 9 States

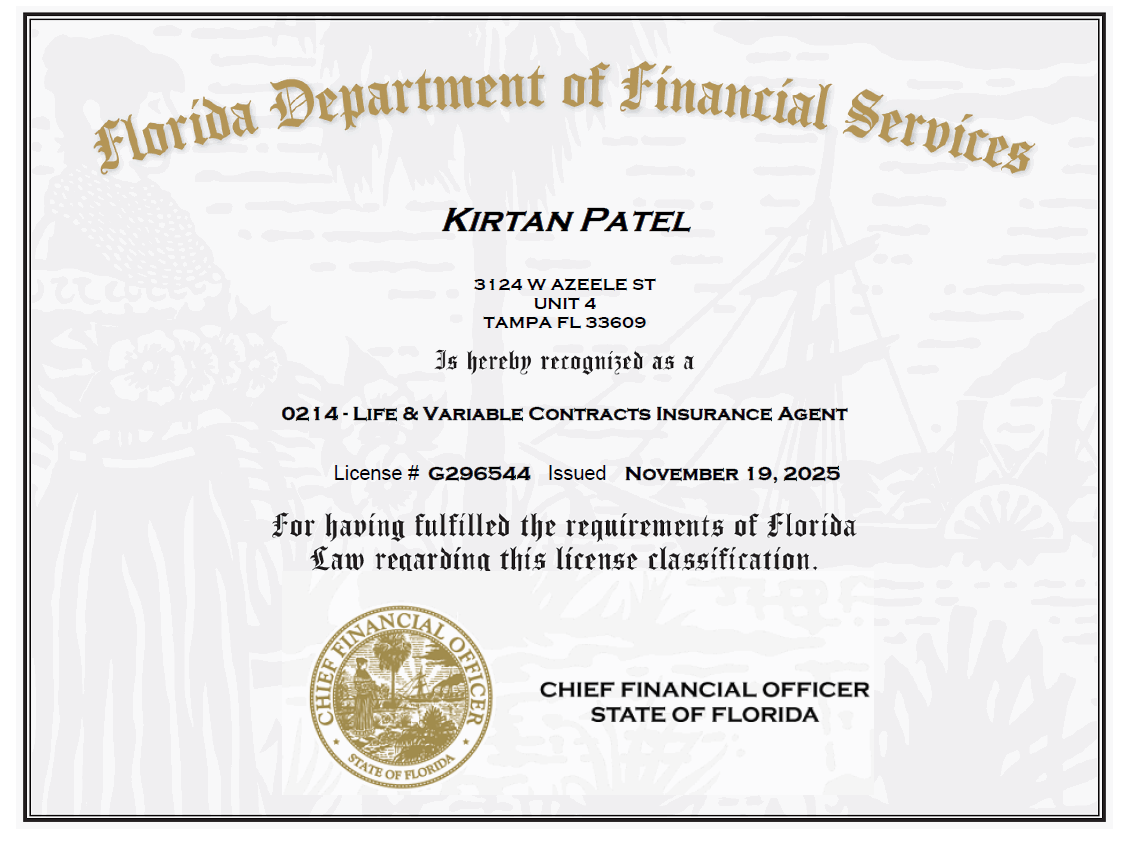
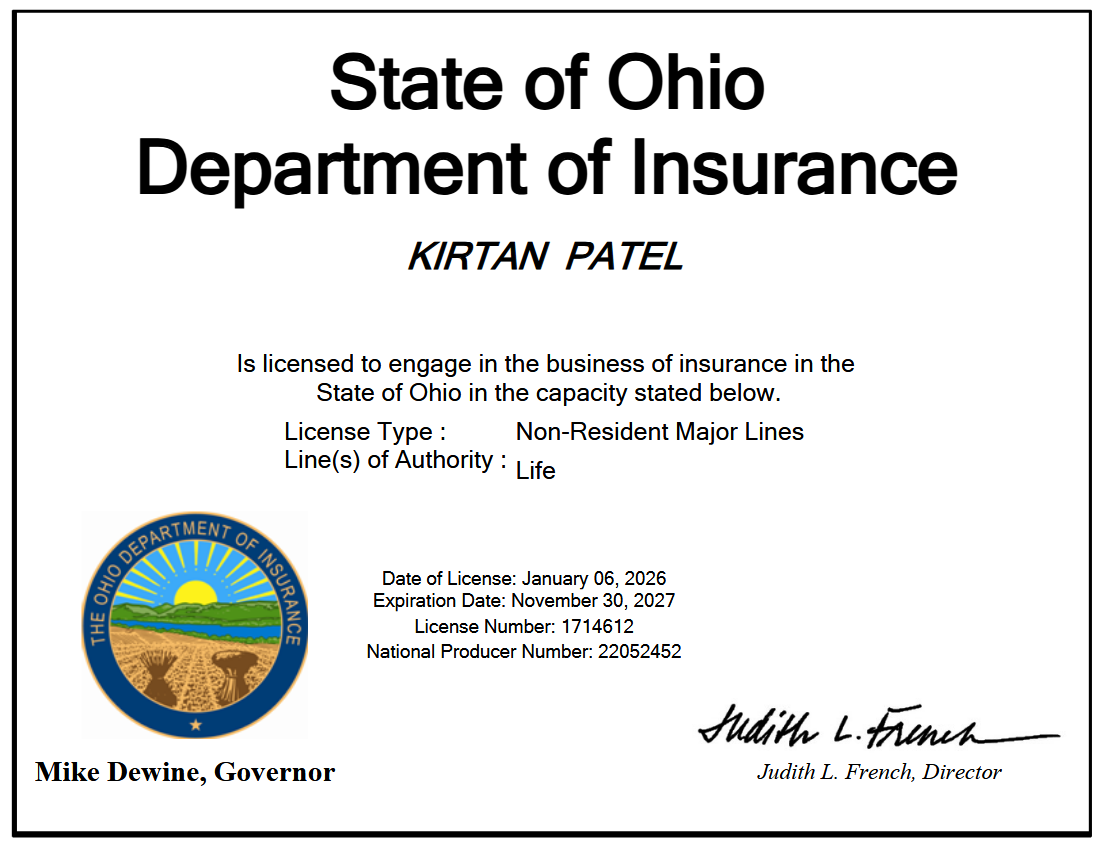
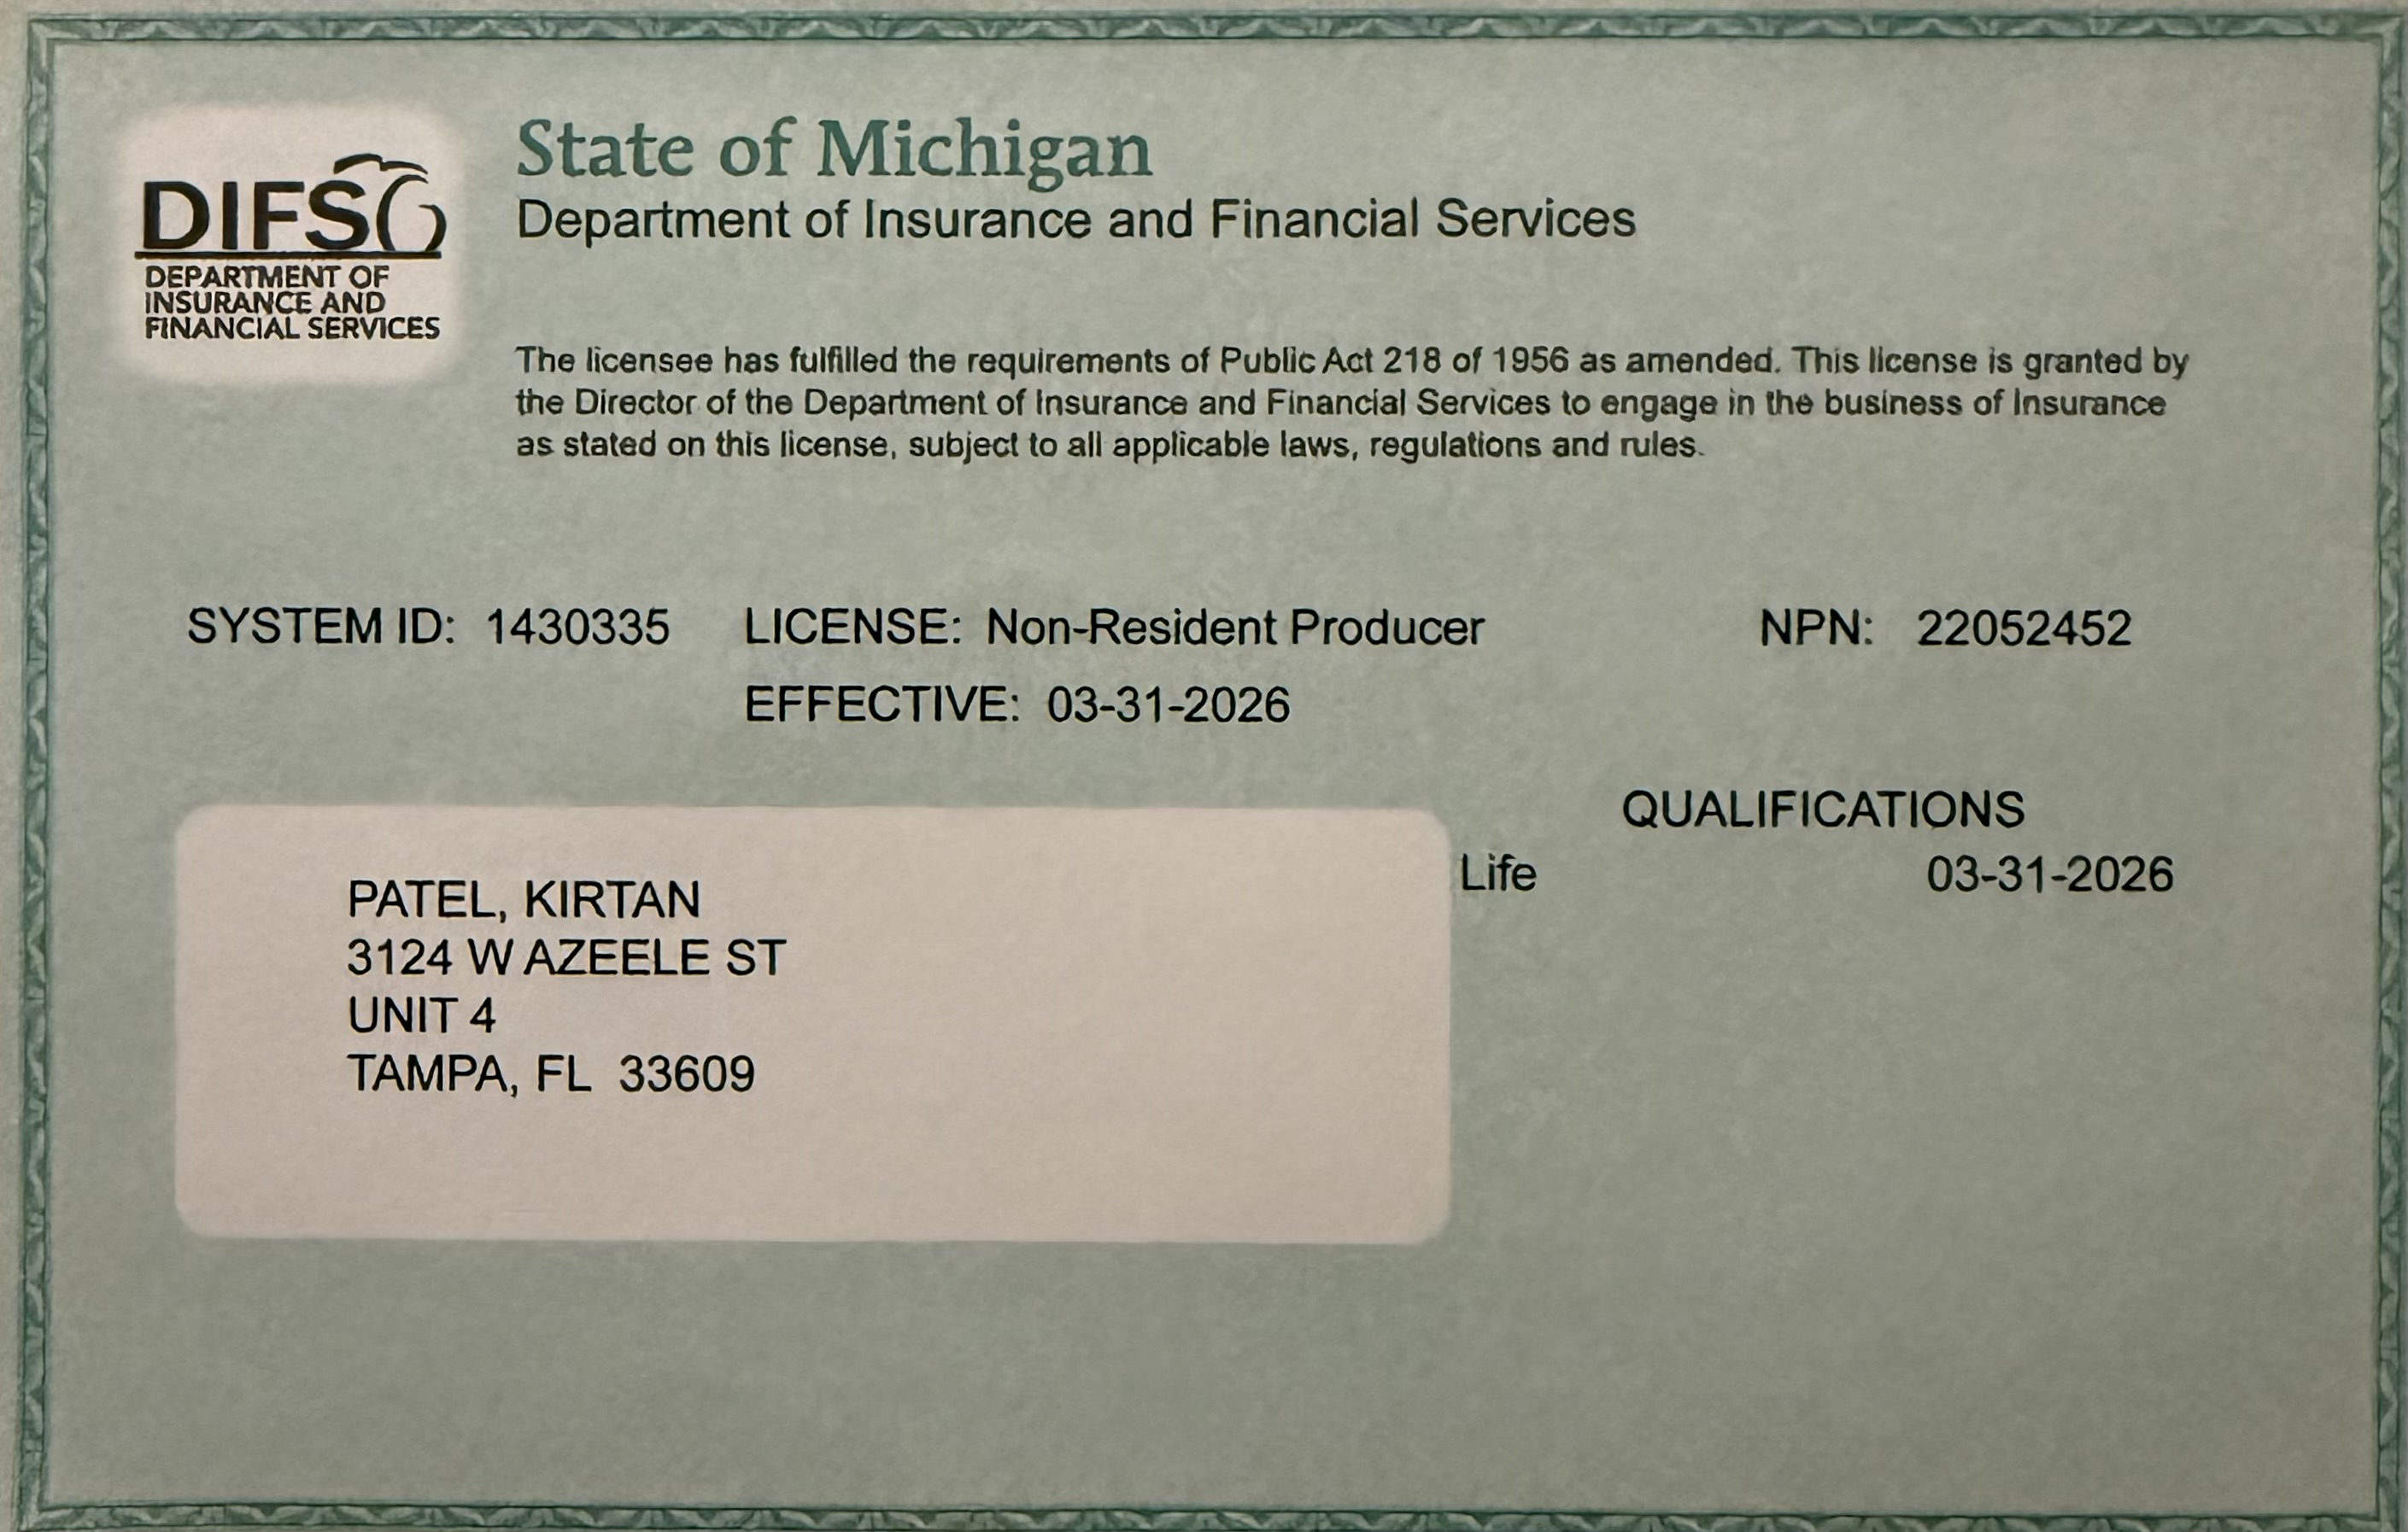
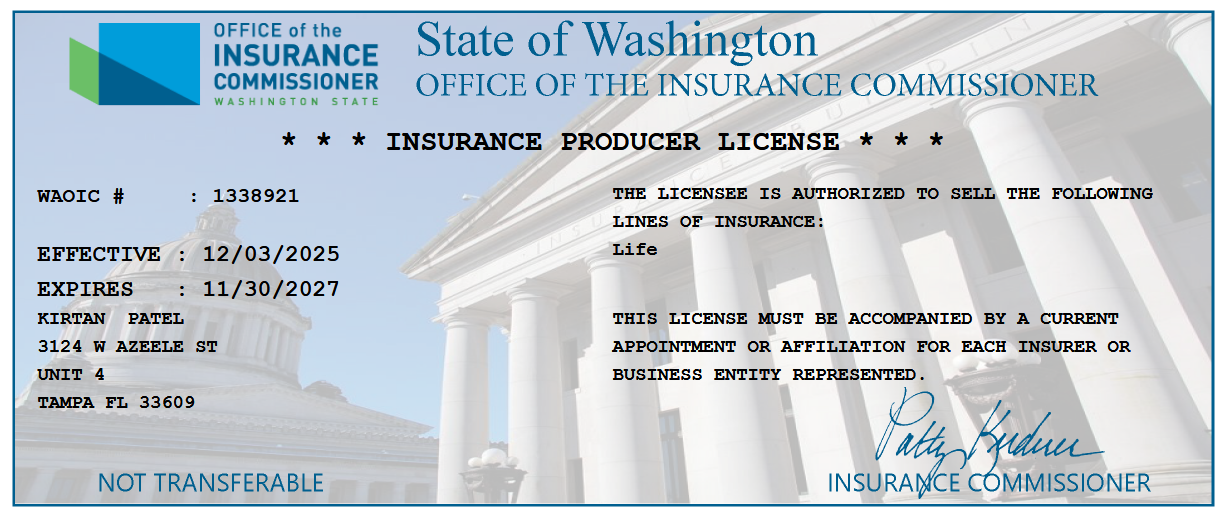
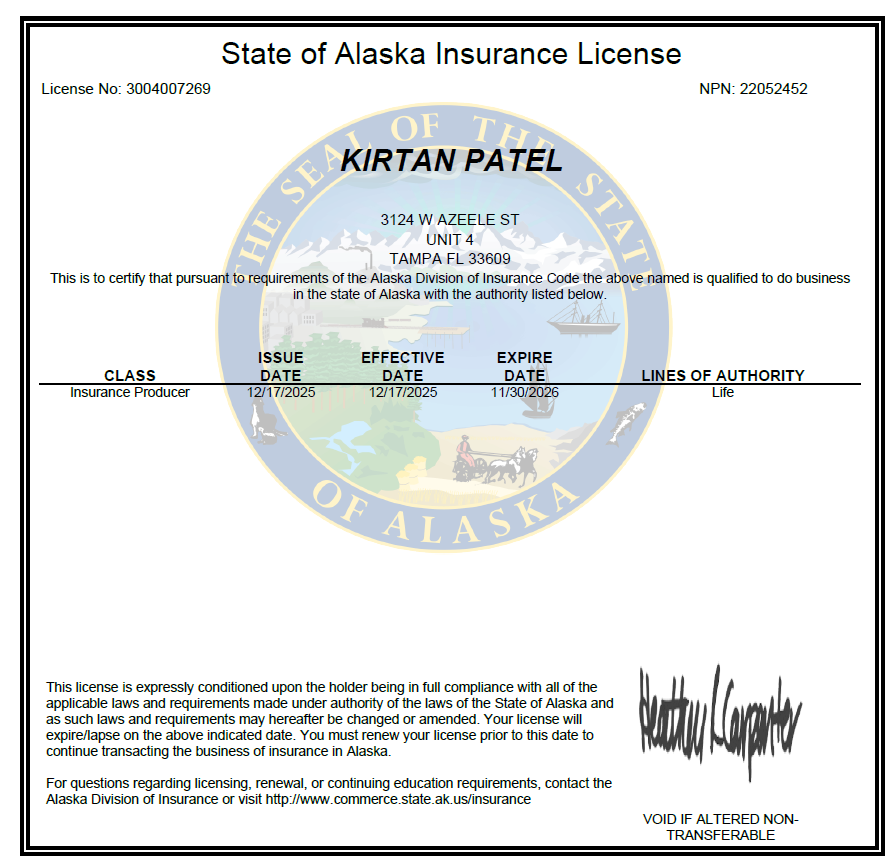
Every license below can be viewed in full because transparency matters. These are the nine states where Kirt is personally licensed. If you live elsewhere, you are still welcome to request help, and Generis Organization may be able to connect you with a trusted advisor licensed in your state.

Florida License
Florida
🔍 Click to view
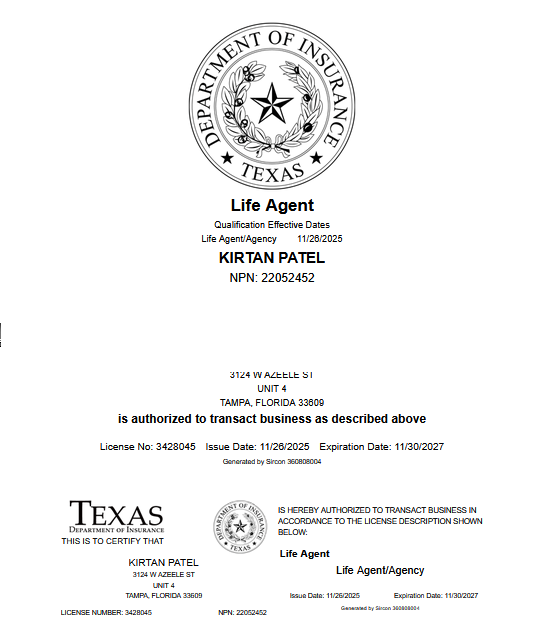
Texas License
Texas
🔍 Click to view
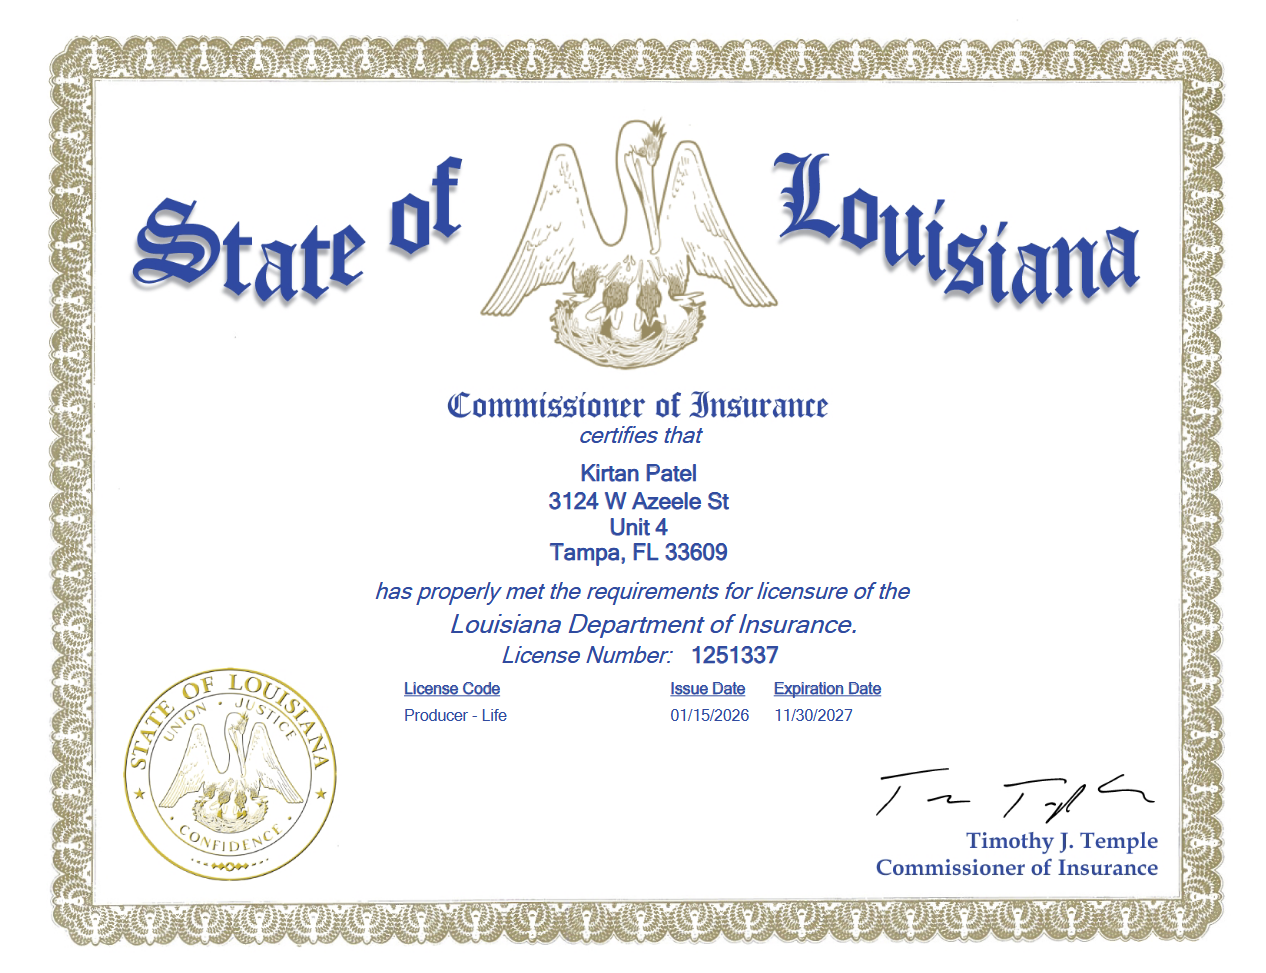
Louisiana License
Louisiana
🔍 Click to view
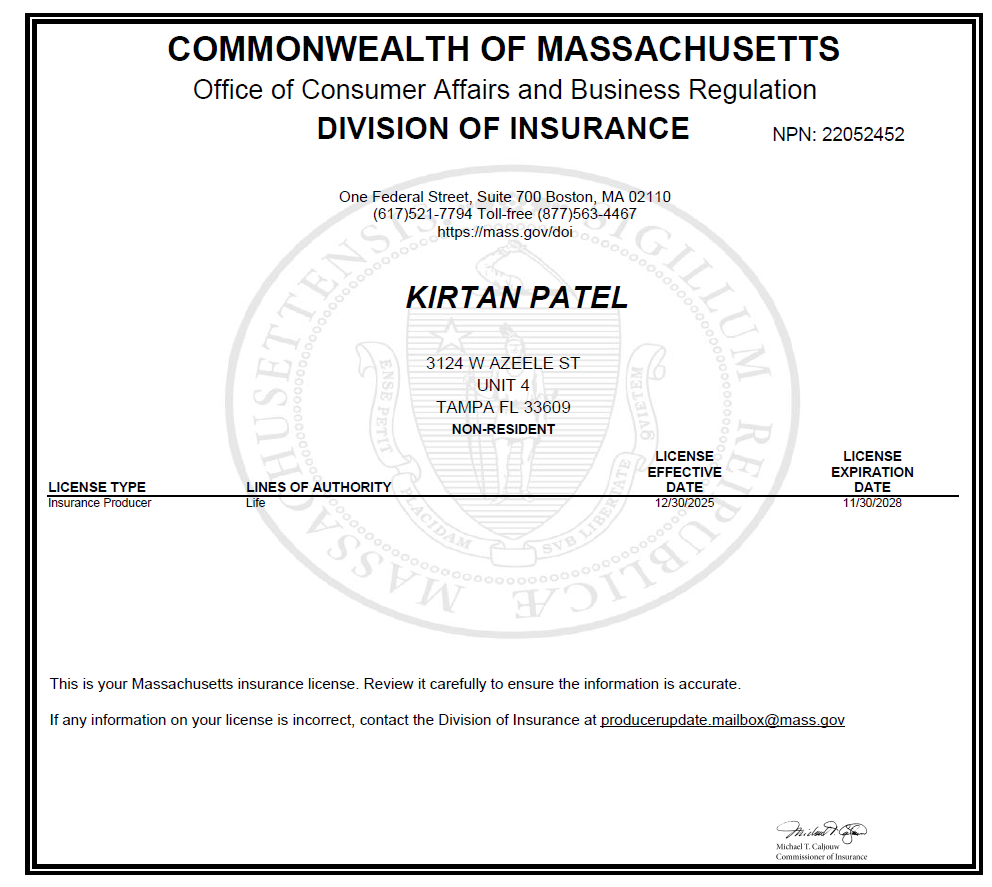
Massachusetts License
Massachusetts
🔍 Click to view
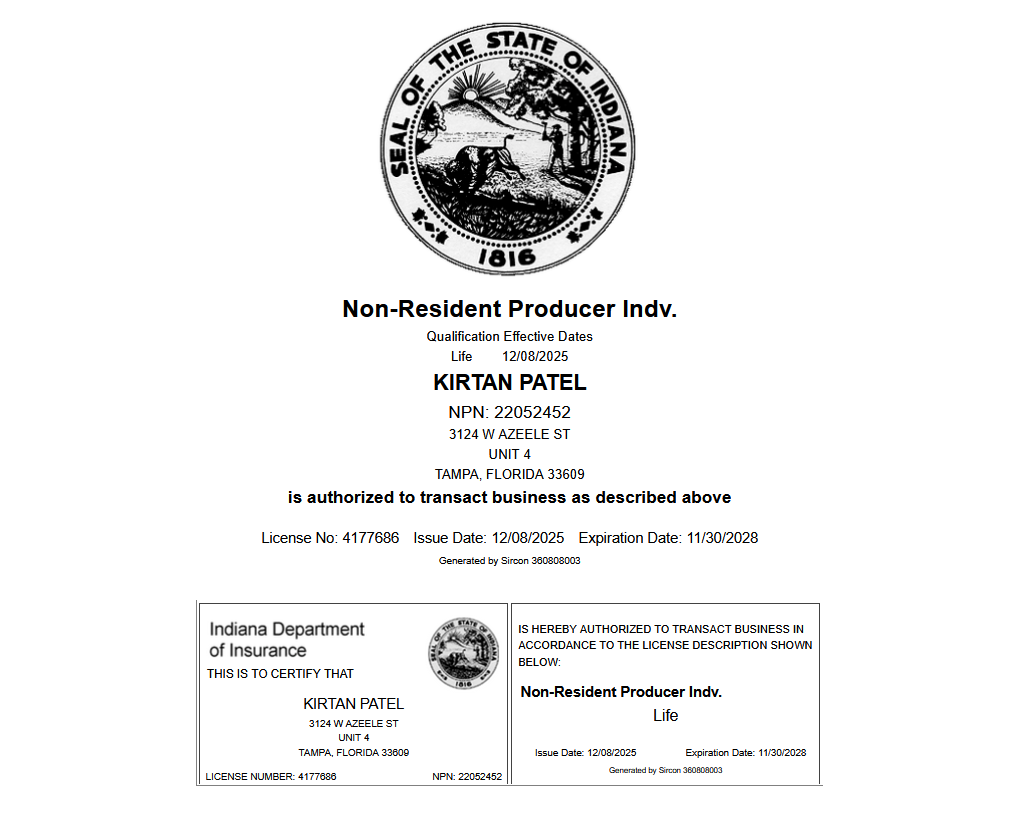
Indiana License
Indiana
🔍 Click to view
Ohio License
Ohio
🔍 Click to view
Michigan License
Michigan
🔍 Click to view
Washington License
Washington
🔍 Click to view
Alaska License
Alaska
🔍 Click to view

Don't see your state?

You're still welcome to request a review. If Kirt is not personally licensed where you live, Generis Organization may be able to connect you with a trusted licensed advisor who is.

Let's tailor your IUL to you and your family.

Answer a few quick questions so Kirt can better understand your goals before you talk. It takes less than 2 minutes to complete.

Step 1 of 8
What are you hoping the IUL will help you accomplish?
Many people choose Indexed Universal Life because it can provide more than just a death benefit.
Step 2 of 8
What is your age range?
Your age helps Kirt understand which coverage options may be appropriate for your situation.
Step 3 of 8
Which state do you live in?
Step 4 of 8
Who are you looking to protect?
Knowing who your beneficiary may be helps Kirt better understand who you're trying to protect before you speak.
Step 5 of 8
What monthly contribution feels comfortable for protecting your family's future?
There's no right or wrong answer. This simply helps Kirt understand which options may fit your budget.
Step 6 of 8
What is your gender?
This helps determine which coverage options may be available to you.
Step 7 of 8
How would you describe your general health?
This helps Kirt understand which insurance companies and coverage options may be worth reviewing.
Last Step — Step 8 of 8
Almost done! Where should Kirt reach you?
Kirt will personally review your information before reaching out so the conversation can stay focused on your goals and the options that may fit your situation.
Required
Required
You'll hear directly from Kirt — not a call center or a group of agents. Your information is never sold. If another licensed advisor is ever needed, Kirt will discuss it with you first and personally make the introduction. Please enter a valid phone number
Please enter a valid email

Prefer to talk? Call Kirt at (469) 436-3768, schedule a consultation, or use the contact page.

Request My Complimentary Review

Personalized illustration · No pressure