Annuities & Retirement Income | Generis Organization
Retirement Income & Protection

Protect Your Retirement Savings &
Create Lifetime Income

As retirement gets closer, protecting what you've already built can matter just as much as continued growth. Kirt Patel, Founder of Generis Organization, helps clients compare fixed and fixed indexed annuity options that may help protect a portion of retirement savings from direct market losses, provide growth potential, and create guaranteed income that can last for life. Have an old 401(k) or IRA? Kirt can also help you review whether repositioning part of those assets could make sense for your retirement.

Request My Complimentary Annuity Review

Complimentary Review • No Obligation • Work Directly With Kirt

Personal Guidance. Clear Answers.

5.0 ★★★★★ Google & Facebook Reviews
Work Directly With Kirt Patel
Independent Guidance
Complimentary Review • No Obligation

Start Your Complimentary Annuity Review

Tell Kirt what you want your retirement money to do — protect savings, create dependable income, or make better use of an old 401(k) or IRA. He'll personally help you understand the available options.

You'll hear directly from Kirt Patel — not a call center or a group of agents. Your information is never sold.

Questions first? Call Kirt or text Kirt, email Kirt, or schedule a consultation.

Want to understand annuities first? Read the educational guide to what an annuity is and how annuities work, see how the main annuity types differ, compare annuities and CDs if you are weighing predictable-interest choices, then explore the options and tradeoffs below before deciding whether a conversation would help.

What Clients Say

Real Experiences. Personal Guidance.

Real reviews from clients across Google and Facebook.

★★★★★ 5.0 Client Reviews
★★★★★

“Kirtan took the time to explain all of my options clearly, without any pressure.”

Working with Kirtan Patel for my life insurance planning has been an exceptional experience. Financial planning can feel overwhelming, but Kirtan took the time to explain all of my options clearly, without any pressure. He helped me structure a plan that protects my family today while building a secure foundation for my retirement. His knowledge, patience, and professionalism gave me complete peace of mind. I highly recommend Kirtan to anyone looking for an honest, trustworthy advisor
Paula C. Reviewed on Google
★★★★★

“He took his time and explained things and did not pressure me into buying anything.”

Mr Kirt Patel treated me with kindness and got me the best deal he could on my life insurance. I am forever grateful because I don’t know a lot on this subject. He took his time and explained things and did not pressure me into buying anything. I believe that is one of the things I liked about him. I do not like being pressured. Thank you again Mr Patel

Tonda K. · Indiana Reviewed on Facebook
★★★★★

“Kirt went above and beyond... KP would call just to check in on me even after i got things all the way str8”

All i can say when i need my life insurance Kirt went above and beyond even though it took a min to get things str8 on my end KP would call just to check in on me even after i got things all the way str8 till this day KP picks up the phone and we just talk great guy Kirt Patel so when y’all reading these reviews just know when you’re looking for great everything this is the company

Selven M. Reviewed on Google

These clients describe their general insurance experience with Kirt and Generis. Their reviews are not annuity performance or product testimonials.

What Can an Annuity Do for Your Retirement?

You worked hard to build your savings. An annuity may help a portion of that money provide more stability, income, or both. The goal is a retirement you can feel more prepared for.

Protect Part of Your Savings

An appropriate fixed or fixed indexed annuity can reduce direct exposure to market losses for the money placed in the contract, while keeping other assets available for other goals.

Create Lifetime Income

Certain income options can turn a portion of your savings into scheduled payments that continue for life, helping cover expenses alongside Social Security or a pension.

Grow Without Direct Stock-Market Exposure

Fixed and fixed indexed annuities offer ways to earn interest without directly investing the contract value in stocks. Interest and access rules depend on the contract.

Reposition an Old 401(k) or IRA

Eligible assets from an old 401(k), IRA, or other retirement account may be repositioned to support greater stability or retirement income. You do not necessarily have to move all of your retirement savings.

An annuity is an insurance contract. Benefits come with access limits and other tradeoffs. A review helps you decide what portion, if any, fits your needs.

Protect What You've Already Built

While you were building your retirement savings, growth may have been the priority. As retirement gets closer, protecting what you've already accumulated can become just as important. A major market loss shortly before or during retirement can be harder to recover from when you are also beginning to take income.

You Don't Have to Move Everything

You don't have to choose between keeping everything invested in the market and moving everything into an annuity. Many retirement strategies use different tools for different jobs.

If part of your 401(k) or IRA is invested in the market, you may choose to reposition only a portion into a fixed or fixed indexed annuity for greater stability or future income while keeping other assets invested or readily available.

Protect Against Direct Market Losses

Many fixed indexed annuities use a 0% floor on index interest credits. If the market index has a negative period, the index-linked interest credit is generally 0% instead of a negative number.

That can help protect the contract from direct market losses, although withdrawals, surrender charges, rider fees, or other contract adjustments can still reduce your account value.

Review My Retirement Options

Keep growth, access, and protection in the same conversation.

Create Income You Cannot Outlive

One of the biggest retirement questions is simple: will your income last as long as you do? Social Security or a pension may cover part of your expenses, but certain annuity strategies can create an additional source of guaranteed lifetime income.

Turn Part of Your Savings Into Income

Certain annuity options can convert part of your retirement savings into guaranteed payments that continue for as long as you live.

Your Income Can Continue Even If the Account Value Reaches Zero

With certain lifetime-income options, payments can continue for the rest of your life even after the contract's account value has been depleted, as long as the contract's requirements are followed.

Choose the Income Option That Fits Your Goals

Different contracts can offer different income options, withdrawal rules, spouse benefits, and beneficiary choices. Kirt will review those details with you before you decide whether anything makes sense.

Lifetime-income guarantees depend on the issuing insurer's claims-paying ability and the specific contract. Taking withdrawals outside the contract's income rules can reduce or end an income benefit, and not every annuity automatically provides lifetime income.

Explore My Lifetime-Income Options

Work directly with Kirt. No obligation to move money or buy.

Have an Old 401(k) or IRA?

If you have an old 401(k), IRA, or other retirement account, retirement can be a good time to decide whether that money should keep chasing growth, become more protected, or begin creating income. You may be able to reposition only a portion while keeping the rest invested or readily available.

Employer Retirement Plan

Old 401(k)

If you've left an employer or retired, eligible 401(k) assets may be moved through a direct rollover without taking possession of the money yourself. An IRA annuity may be one option for the portion you want positioned for protection or future income.

Individual Retirement Account

IRA

IRA assets can often be moved directly from one custodian to another through a trustee-to-trustee transfer. This can allow you to reposition part of your retirement savings without taking possession of the funds yourself.

Money Outside Retirement Accounts

Lump Sum or Savings

An annuity can also be funded with non-retirement money, such as savings, a CD, or another lump sum. This may be worth reviewing if your goal is more predictable growth, protection, or future income.

A Direct Rollover Can Help Keep the Process Simple

When eligible pre-tax retirement assets are moved through a properly completed direct rollover, they can generally continue their tax-deferred treatment without being paid to you first. That also avoids the mandatory federal withholding that normally applies when an eligible employer-plan distribution is paid directly to you.

Not every retirement-plan distribution is eligible for rollover. Required minimum distributions and certain other payments cannot be rolled over, and Roth conversions can create taxable income. Before moving anything, compare your current plan's costs, protections, access, and benefits with the new option.

An annuity inside an IRA does not create an extra layer of tax deferral, so the reason to consider one should be its insurance features — such as protection or income — not additional tax deferral. Talk with a qualified tax professional about your individual situation. Read the IRS rollover guidance.

Three Approaches to Retirement Annuities

More predictable interest, a different way to grow, or income that starts soon: each approach serves a different need.

Predictable Interest

Fixed Annuities

A predictable-interest option for people who value stability. The insurer credits interest under the contract, often with a rate guaranteed for a set period.

What to review: How long the rate lasts, what happens afterward, and when you can access the money.

Learn how fixed annuities work →

Growth Potential With a Floor

Fixed Indexed Annuities

Earn interest based partly on a market index's performance without directly investing your contract value in that index. Growth is limited by the contract's rules.

What to review: How much of an index increase can be credited, any fees, and whether an income option fits.

Learn how fixed indexed annuities work →

Turn Savings Into Payments

Immediate / Income Annuities

Turn a lump sum into a predictable stream of retirement income. Immediate annuities generally begin paying soon; other income arrangements may start later.

What to review: Whether payments last for life or a set period, what access remains, and what a beneficiary receives.

Product availability, features, and eligibility vary by state, insurer, contract, and individual circumstances.

Who May Want an Annuity Review?

An annuity review may be worth having if you're approaching retirement, want more predictable income, or simply want to reduce how much of your future depends on market performance. These are common reasons people start the conversation.

You're approaching retirementYou want to protect more of what you've accumulated and start planning how those savings can support you for the years ahead.

You want more predictable retirement incomeYou'd like to know whether part of your savings could create guaranteed payments to help cover monthly expenses for life.

You're more concerned about safety than maximum growthYou want part of your retirement savings protected from direct market losses while still keeping some opportunity to earn interest.

You want to compare fixed and fixed indexed annuitiesYou have retirement assets and want to understand which type may offer the right balance of stability, growth potential, and access.

You want income that can last for lifeYou want to understand how lifetime-income options work, when payments can begin, and what happens for a spouse or beneficiary.

You have an old 401(k), IRA, or savings you want to reviewYou want to see whether repositioning part of those assets could improve retirement safety or future income without moving everything.

Pause and compare other options if...

  • You need near-term access to most of the money or do not have adequate emergency reserves.
  • You need short-term flexibility or cannot explain the surrender restrictions in your own words.
  • The proposed contract does not match your goals, or you have not compared alternatives.

A Personal Conversation.
A Decision You Can Understand.

Kirt Patel is a licensed life insurance advisor and independent insurance broker specializing in life insurance, annuities, and retirement-income strategies. He works directly with clients to understand their goals, compare appropriate options, and explain the details clearly so they can make informed, confident decisions.

Understand It Before You Buy It

Kirt will explain how the annuity works, what it may do for you, how you can access your money, and what the tradeoffs are before you decide whether to move forward.

Independent Guidance

Kirt's role is to help you find the approach that makes the most sense for your retirement goals — even if that means keeping part or all of your current strategy instead of purchasing an annuity.

Personalized Retirement Review

Kirt will look at what you want your money to do, when you'll need it, how much access you want to keep, and whether safety, growth, lifetime income, or a combination matters most.

Long-Term Support

Kirt's relationship with clients doesn't end when a contract is issued. He remains available for future reviews, beneficiary questions, income decisions, and changes to retirement needs.

Work Directly With Kirt

Your request comes directly to Kirt — not a call center or a group of agents. He'll personally review your situation, answer your questions, and stay involved throughout the process.

Three Steps. No Pressure.

Your review starts with a simple conversation about your retirement goals, the money you're considering, and what matters most to you. Kirt will help you understand the options before you decide whether anything makes sense.

1

Request Your Complimentary Review

Share a few details and Kirt will personally reach out to learn what you're trying to accomplish with your retirement savings.

2

Review Your Goals and Options

Kirt will discuss when you plan to retire, how much access you want to keep, whether safety or income matters most, and which annuity approaches may be worth considering.

3

You Decide What Makes Sense

Kirt will explain the benefits, costs, access rules, and tradeoffs. Then you decide whether to move forward, keep your current strategy, or do nothing at all. There's no pressure and no obligation.

What Should You Know Before Choosing an Annuity?

An annuity can provide valuable protection or income, but those benefits come with rules and tradeoffs. Kirt will help you understand both the advantages and the limitations before you make a decision. Compare annuity pros and cons →

Access to Your Money

An annuity usually should not hold money you may need for emergencies or short-term expenses. Many contracts allow some withdrawals, but taking more than the allowed amount can trigger charges or reduce future benefits.

Surrender Periods

Many annuities are designed to be held for several years. If you withdraw too much or leave the contract early, surrender charges may apply. Some contracts may also adjust the amount you receive based on interest-rate conditions.

Income vs. Access

Creating more predictable or guaranteed income can mean giving up some access to the original money. Kirt will review how much flexibility remains, any income-related fees, and what happens for a spouse or beneficiary.

How Indexed Interest Works

With a fixed indexed annuity, you do not receive the full return of the market index. The contract uses rules that determine how much interest is credited. Many use a 0% floor on index credits, but fees, charges, or withdrawals can still reduce the account value.

The Insurance Company Matters

Annuity guarantees are backed by the insurance company that issues the contract, so the strength and reputation of the carrier matter. An annuity is not an FDIC-insured bank account, and fixed payments may lose purchasing power over time.

Taxes & Retirement Accounts

How an annuity is taxed depends on where the money comes from and how it is withdrawn. An IRA already grows tax-deferred, so placing an annuity inside an IRA does not create additional tax deferral. Speak with a qualified tax professional about your individual situation, and review the educational guide to how annuities are taxed.

The right fit matters more than the highest advertised rate. A good annuity decision should consider your retirement goals, income needs, access to money, costs, and the alternatives available to you. General information on this page is not individual tax or investment advice.

Work With an Established Annuity Carrier

F&G

F&G

F&G is an established insurance company offering fixed and fixed indexed annuities designed for goals such as retirement savings protection, interest-crediting potential, and lifetime income. Kirt can help you understand which available options may fit your goals and how the contract works before you decide whether to move forward.

Product availability and features vary by state and contract. Not every F&G product is available in every situation. Learn more about F&G annuities.

Clear Answers Before You Decide

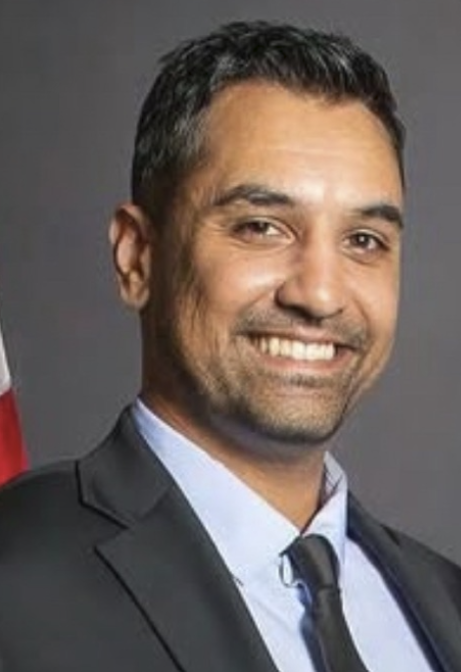
Kirt Patel

Personal Guidance for Your Retirement Decisions

Founder of Generis Organization • Independent Life Insurance Advisor and Broker

Retirement decisions can feel complicated, but they shouldn't feel confusing. I take the time to understand what you're trying to accomplish, explain your options clearly, and help you make a decision you feel comfortable with.

I specialize in life insurance, annuities, and retirement-income strategies. Whether your goal is protecting part of your savings, creating lifetime income, reviewing an old 401(k) or IRA, or understanding an annuity you already own, I'll help you compare the available insurance-based options.

You work directly with me from the first conversation forward. We'll compare what each option is designed to do, how much access you keep, the costs and tradeoffs, and whether it actually fits your retirement goals.

And if you do move forward, my relationship with you doesn't end when the contract is issued. I'll remain available for future reviews, beneficiary questions, income decisions, and changes to your retirement needs.

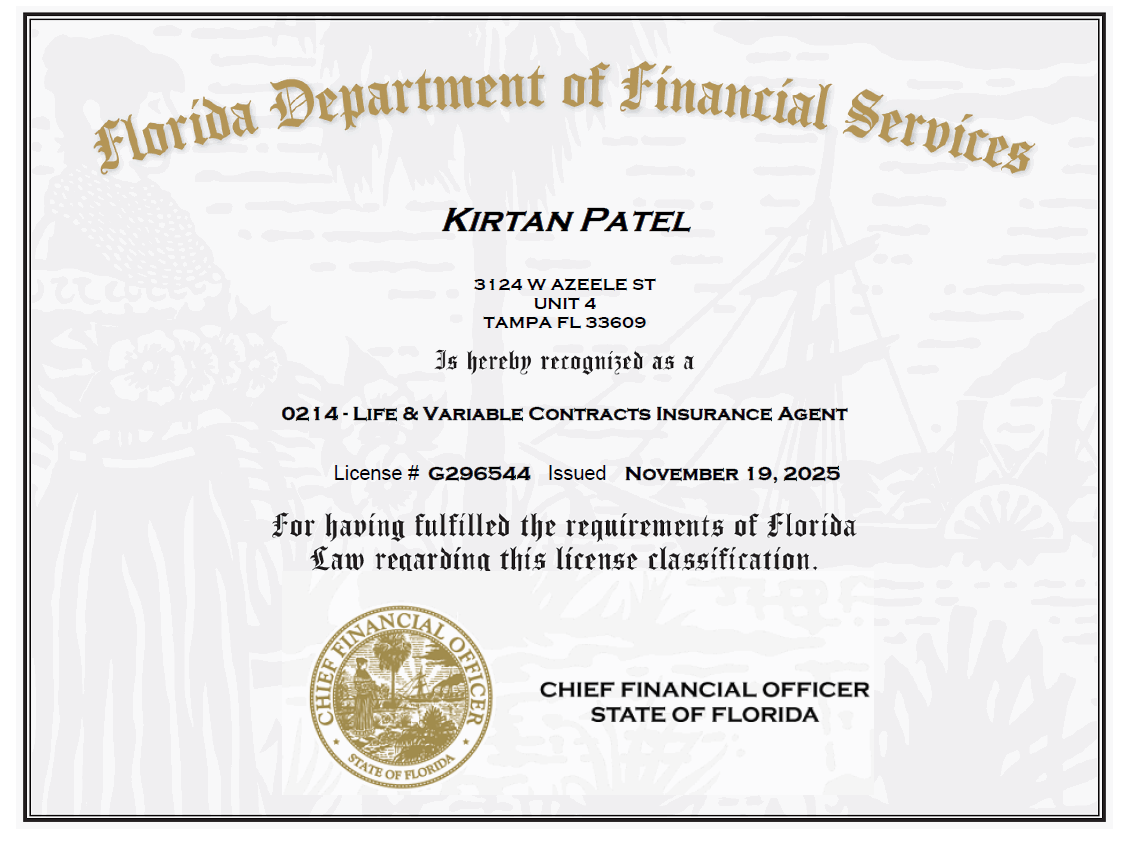
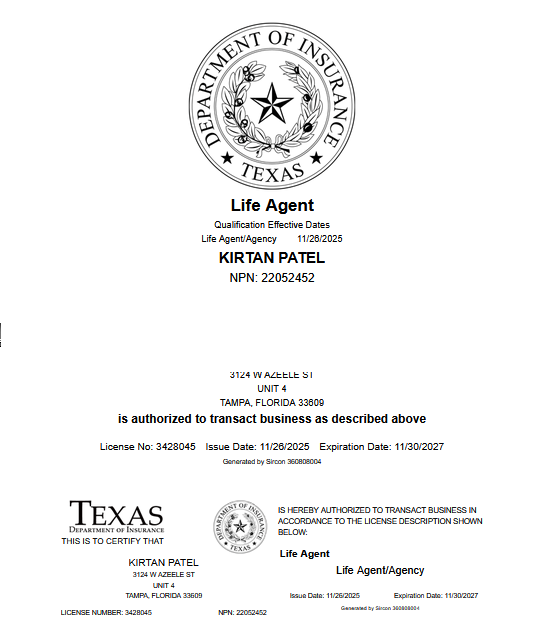
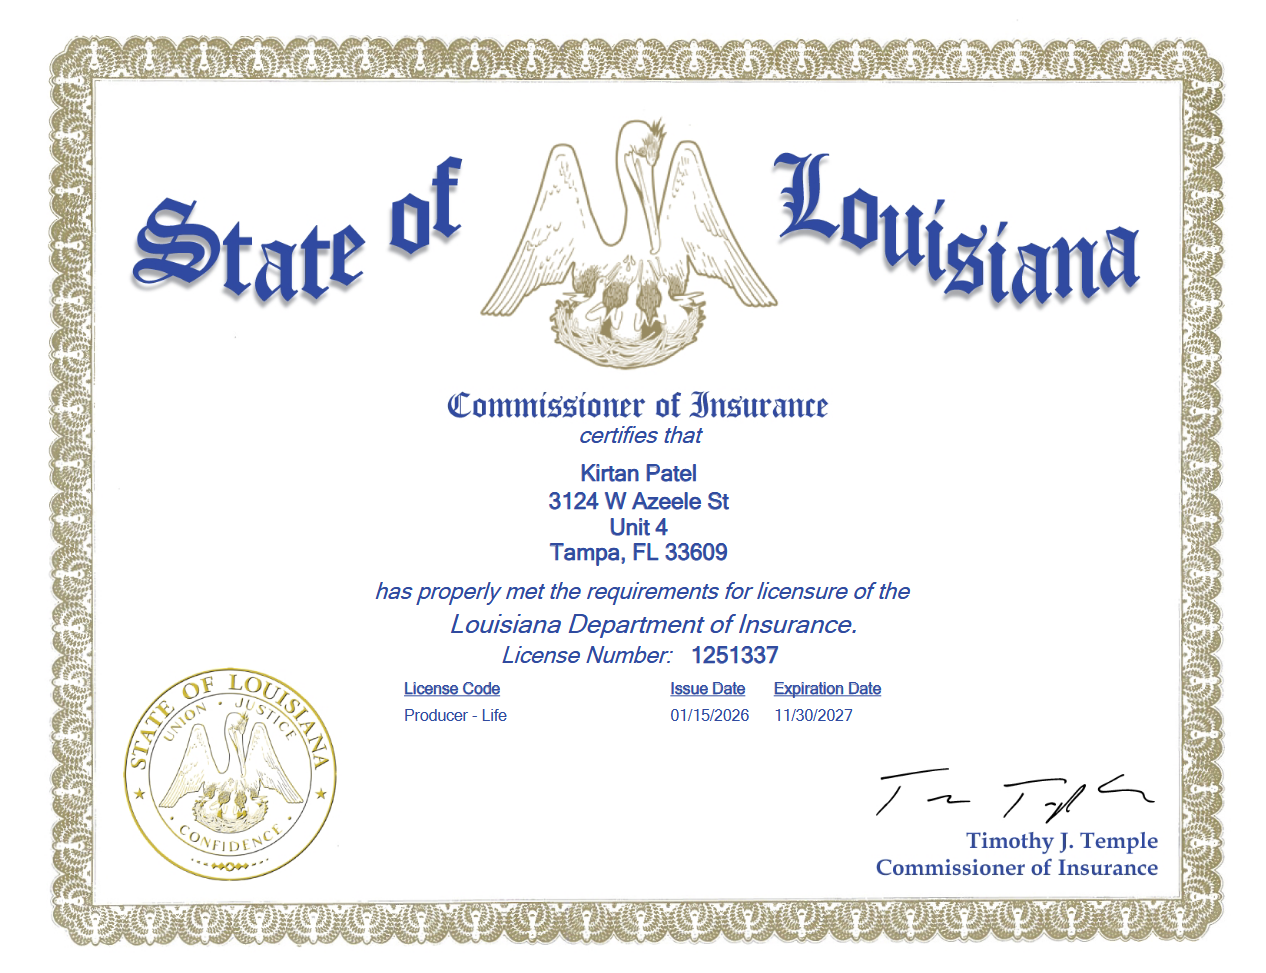
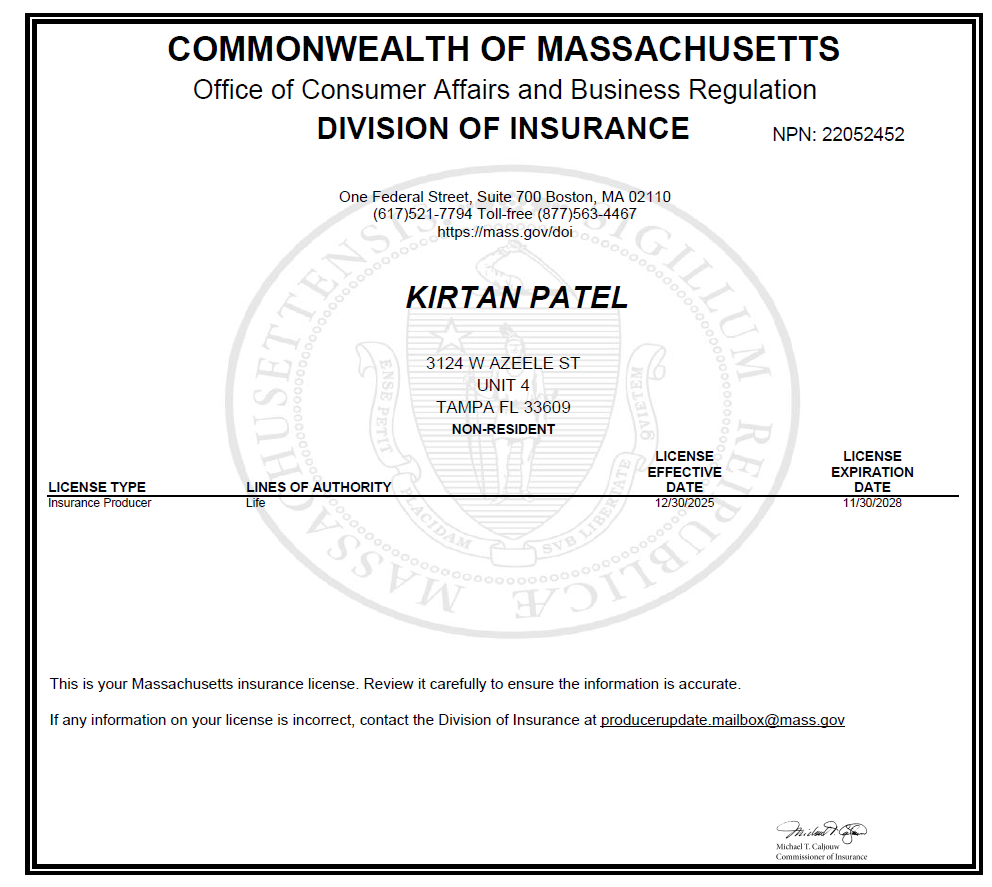
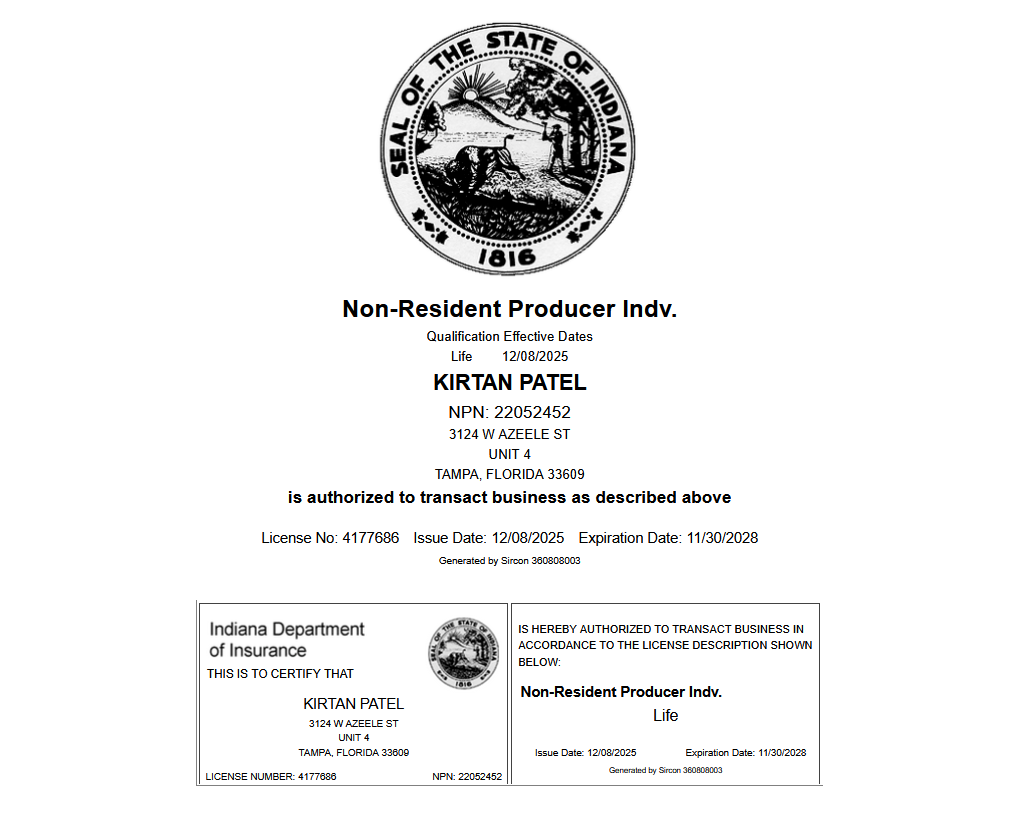
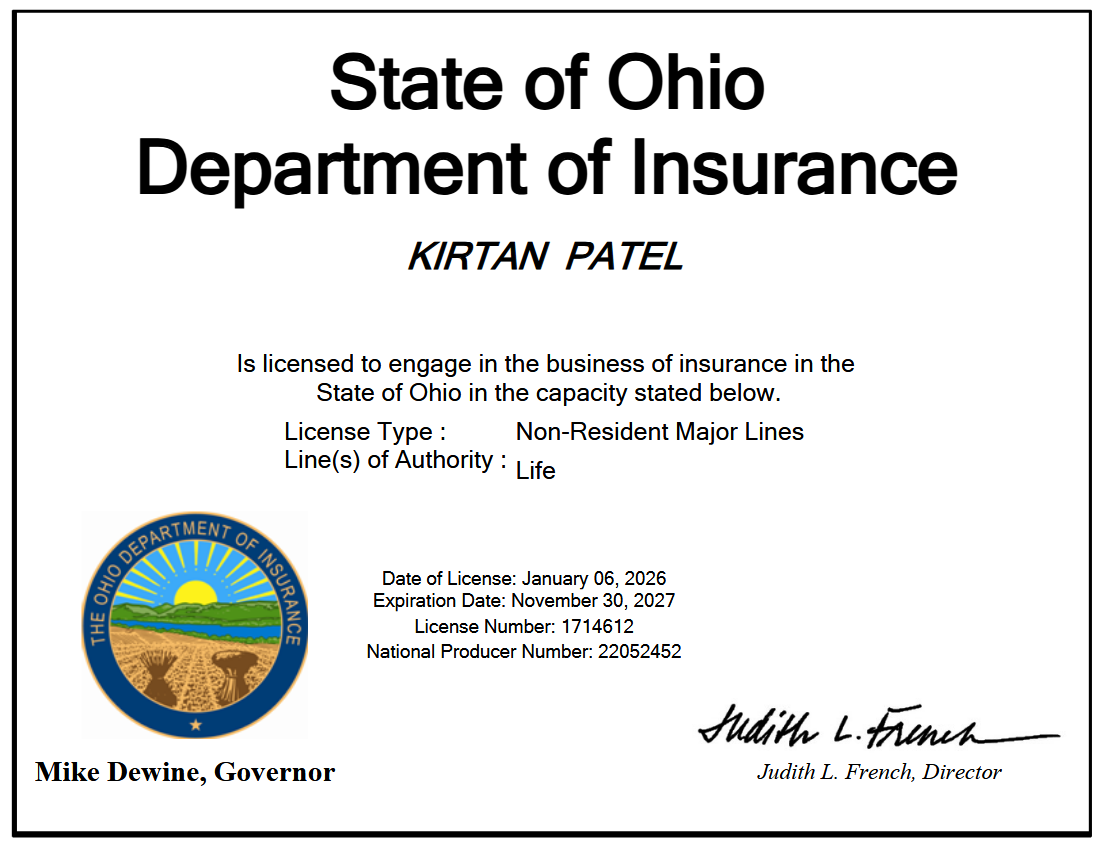
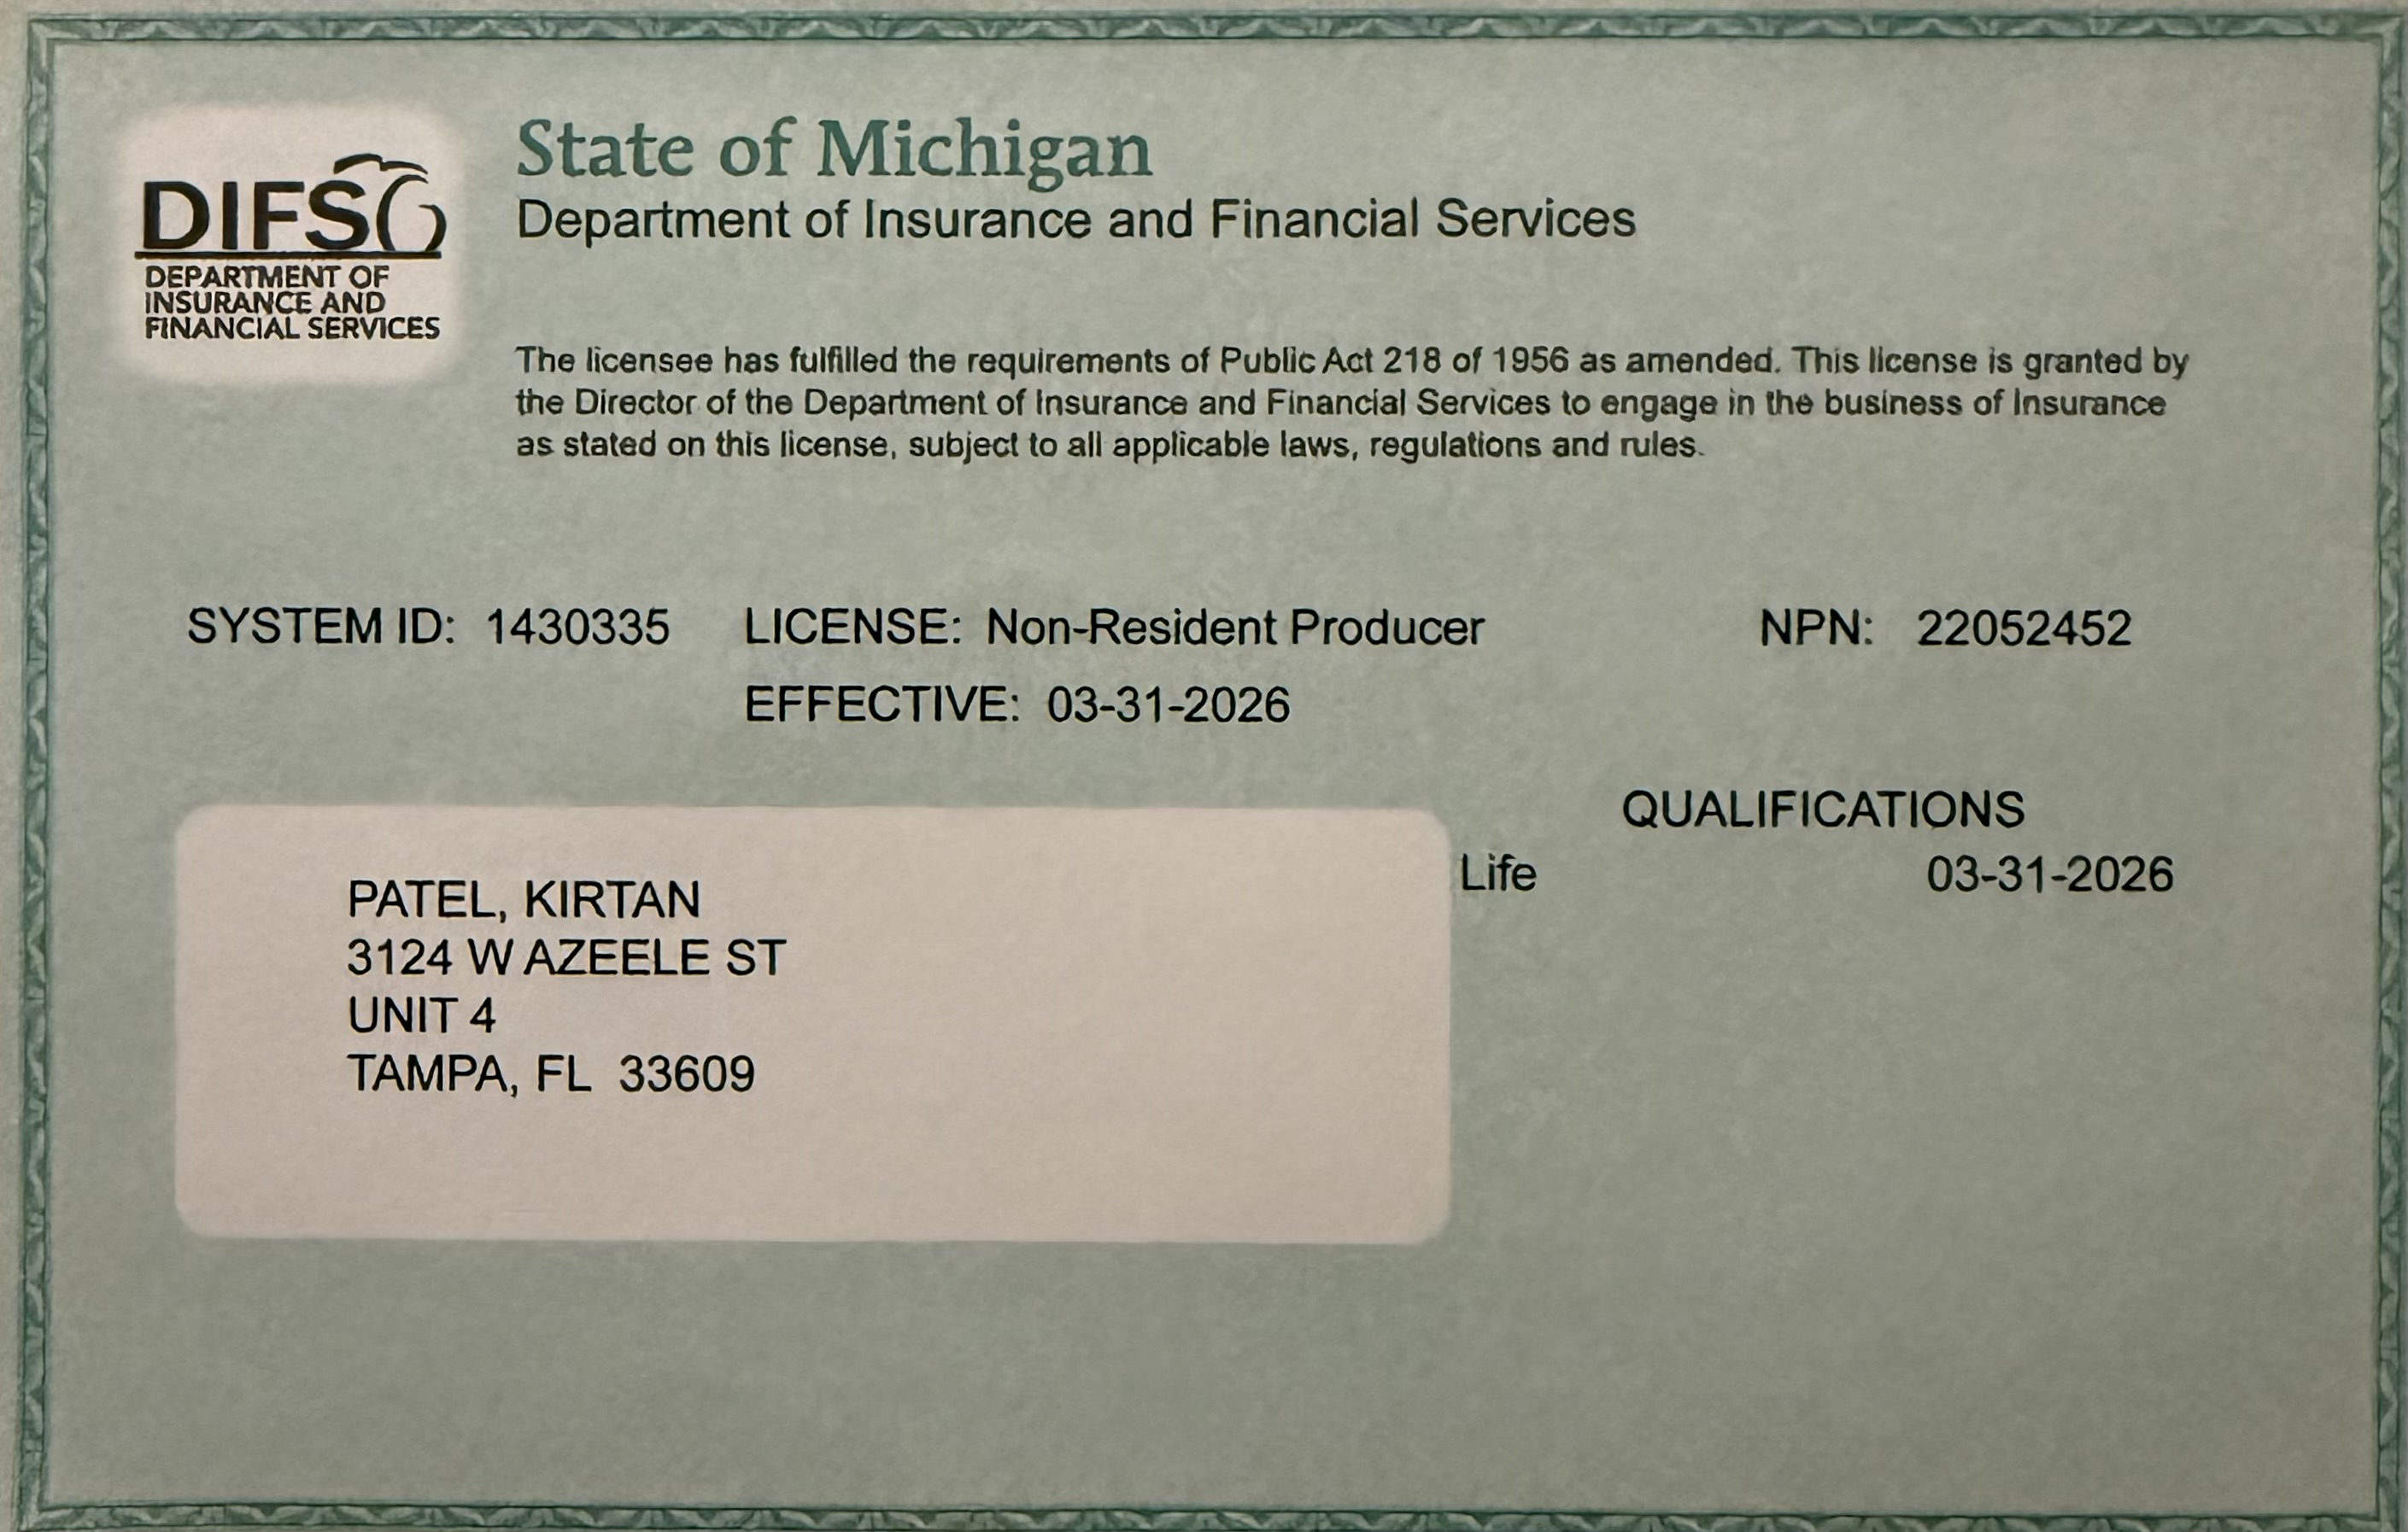
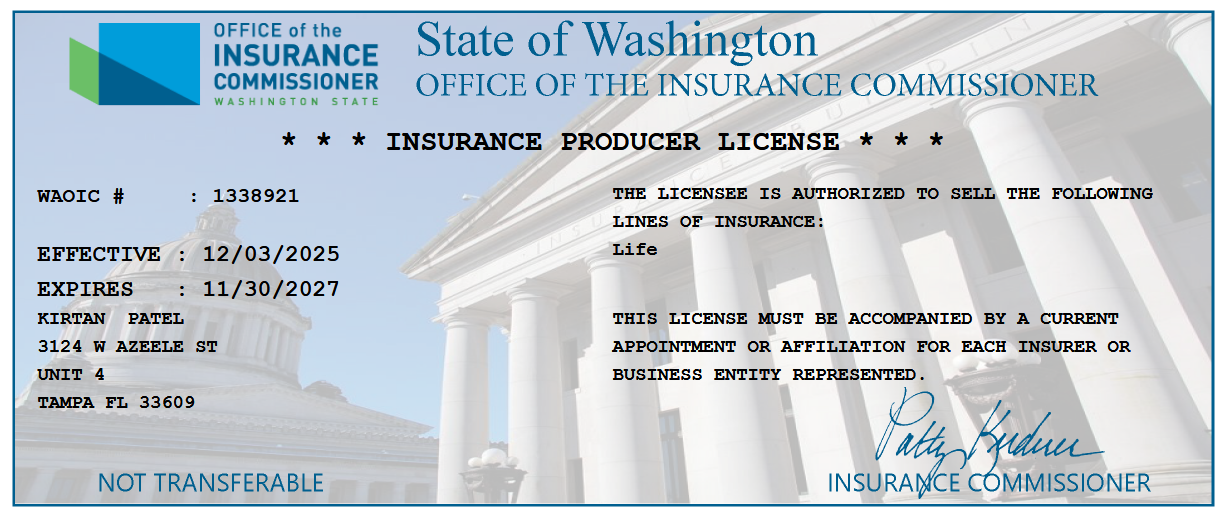
Personally Licensed Across 9 States

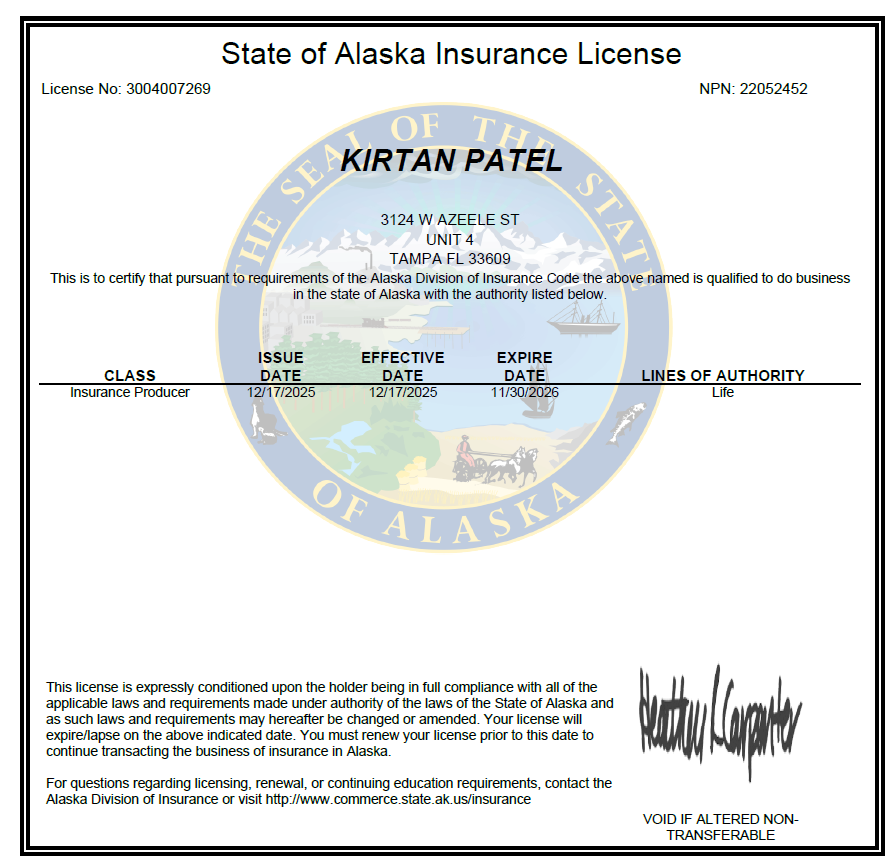
Every license below can be viewed in full because transparency matters. These are the nine states where Kirt is personally licensed. If you live elsewhere, you are still welcome to request help, and Generis Organization may be able to connect you with a trusted advisor licensed in your state. Product availability, features, and eligibility vary by state, insurer, contract, and individual circumstances.

Florida License
Florida
🔍 Click to view
Texas License
Texas
🔍 Click to view
Louisiana License
Louisiana
🔍 Click to view
Massachusetts License
Massachusetts
🔍 Click to view
Indiana License
Indiana
🔍 Click to view
Ohio License
Ohio
🔍 Click to view
Michigan License
Michigan
🔍 Click to view
Washington License
Washington
🔍 Click to view
Alaska License
Alaska
🔍 Click to view

Don't see your state?

You're still welcome to request a complimentary review. If Kirt is not personally licensed where you live, Generis Organization may be able to connect you with a trusted licensed advisor who is.

Let's Put Your Retirement Goals First

Answer a few quick questions so Kirt can better understand your retirement goals before you talk. No account numbers, medical exam, or commitment to move money — just the information needed to make the conversation more useful.

Step 1 of 7

What would you most like help with?

Choose the goal that matters most to you right now.

What would you most like help with?

Prefer to talk? Call Kirt at (469) 436-3768, schedule a consultation, or use the contact page.