Sales, client relationships, or revenue may depend heavily on a founder, owner, or key employee.
Business Life Insurance
Protect the Business You Worked to Build
During your complimentary Business Protection Review, Kirt Patel, Founder of Generis Organization and an independent life insurance advisor and broker, will help identify what your business needs to protect and compare options from multiple insurance companies.
Request My Business Protection Review✓ Complimentary Review • No Obligation
Why Business Owners Trust Generis
Business Protection Review
Start Your Complimentary Business Protection Review
Share a few details and Kirt will help you identify what may need protecting before discussing the solution.
offAvailable Now
📞 Tap to Call Kirt Now📞 Call Kirt Now — (469) 436-3768
Or submit the short form below and Kirt will call you as soon as possible.
Prefer another way to connect? Call Kirt, text Kirt, email Kirt, or schedule a consultation.
Business Life Insurance Explained
What Is Business Life Insurance?
Business Life Insurance is not one specific type of policy. It is life insurance used to help protect a business from financial loss tied to owners, key employees, debt, ownership transfers, serious illness, and other continuity needs. Depending on the policy and available riders or features, coverage may also provide living benefits after a qualifying critical illness, chronic illness, or terminal illness. The business need comes first; the policy type and features come second.
- Key Person protection
- Buy-Sell funding
- Owner protection
- Business debt
- Business continuity
- Succession funding
Why Business Protection Matters
Where Could Your Business Face a Financial Gap?
If an owner, partner, or key employee dies, becomes seriously ill, or is unable to work for an extended period—or if an ownership transfer needs funding—the financial impact can reach far beyond one person. A Business Protection Review helps identify which risks matter to your company and whether life insurance, including available living-benefit features, could help.
Replacing specialized knowledge, leadership, or experience can take time and require additional working capital.
Partners, shareholders, or family members may need funding to complete an orderly ownership transfer.
Business loans, guarantees, payroll, leases, and other obligations may continue during a transition.
Serious Illness & Living Benefits
How Can Serious Illness Disrupt the Business?
Business disruption does not always begin with a death. A serious illness can reduce an owner's or key employee's ability to work, lead the business to hire temporary or permanent help, interrupt revenue, or create additional pressure on cash flow and operations.
Some life insurance policies include or offer living-benefit or accelerated-benefit features that may provide access to a portion of the policy's death benefit—or another rider benefit—after a qualifying critical illness, chronic illness, or terminal illness.
- Lost productivity or revenue
- Temporary or permanent replacement costs
- Payroll, debt, and continuing obligations
- Time to recover, restructure, or transition
Common Business Protection Needs
What Does Your Business Need to Protect?
Business Life Insurance can serve different purposes. Your review can focus on one need or several, depending on how your company is structured and what could create the greatest financial strain.
Key Person or Key Employee
Help protect the business from the financial impact of losing an owner, leader, specialist, or other person who may be difficult to replace.
Business Owners or Partners
Provide funding that may help complete an ownership transfer under a Buy-Sell agreement.
Business Debt or Loans
Review loans, personal guarantees, collateral assignments, and other obligations that could affect the business after a death.
Family and Business
Separate personal family protection from the coverage needed to protect the company, ownership interests, or both.
Business Continuity
Plan for the financial impact of leadership, ownership, or succession changes that could affect the business over time.
Key Person Insurance
Protect the Business From the Loss of a Key Person
A key person may be an owner, executive, revenue producer, specialist, or relationship holder whose death could materially affect revenue, operations, client retention, or continuity. Key Person Insurance can provide financial resources to help the business respond while it replaces the person, stabilizes operations, and protects important obligations or relationships.
- Recruiting and replacement costs
- Lost revenue or client relationships
- Working capital and continuing obligations
- Time to stabilize operations
Buy-Sell Funding
Would the Business Have the Funding to Transfer Ownership?
Life insurance can provide funding to help complete an ownership transfer after an owner's death. That can give the business, surviving owners, and the owner's family a clearer financial path without relying entirely on company cash or the sale of business assets.
The right funding arrangement depends on the Buy-Sell agreement, ownership structure, business value, and tax considerations. Those details should be coordinated with the business's attorney, CPA, or other qualified professionals.
Business Debt Protection
What Happens to Business Debt if an Owner Dies?
Life insurance may help provide funds for business loans, personal guarantees, lender requirements, or other obligations that could remain after an owner's death. The review should focus on what is owed, who would be responsible, and how much cash the business may need to stay financially stable.
Requirements vary by lender, loan, borrower, and situation. Some lenders may request life insurance or a collateral assignment, but not every business loan or SBA loan requires it.
Business and Personal Protection
Your Business and Your Family May Need Different Protection
As a business owner, you may need coverage for your family, your company, and your ownership interests. Those needs can overlap, but they may require different coverage amounts, policy structures, owners, or beneficiaries.
Existing personal life insurance can be reviewed alongside your business needs so you can see what is already covered and where gaps may remain. You can also learn more about Term Life, Whole Life, and Indexed Universal Life.
How Much Coverage?
How Much Business Life Insurance Is Enough?
The right amount depends on what the policy is intended to protect. A Key Person need, Buy-Sell obligation, business loan, or owner-protection need may each require a different approach to determining coverage.
- Revenue tied to a key person
- Replacement cost and transition time
- Compensation and replacement expense
- Outstanding business debt
- Ownership value or Buy-Sell obligation
- Ownership-transfer funding need
- Available business liquidity
- Transition and continuity expenses
Policy Ownership
Who Should Own the Policy and Receive the Benefit?
In business life insurance, the insured person, policy owner, premium payer, and beneficiary may not all be the same person or company. The right structure depends on the purpose of the coverage, the business arrangement, and who is intended to receive the benefit.
The Generis Difference
Why Business Owners Work With Kirt Patel & Generis Organization
Business protection can involve owners, key employees, debt, agreements, and family interests. Kirt's role is to help you understand what needs protection, compare appropriate options from multiple insurance companies, and explain the tradeoffs clearly before you decide.
Work Directly With Kirt
Your review goes directly to Kirt Patel—not a call center or rotating group of agents.
Independent Advice
Kirt can compare options from multiple insurance companies instead of being limited to one carrier's products.
Business Need First
The conversation starts with what the business needs to protect before deciding which type of life insurance may fit.
Coordinate With Your Advisors
When legal, tax, valuation, or agreement questions are involved, Kirt can help keep the insurance side aligned with your attorney, CPA, lender, or other professionals.
Support as Your Business Changes
Coverage can be reviewed as ownership, debt, key people, and other business circumstances change over time.
The Review Process
What Happens During Your Business Protection Review
Understand What You Need to Protect
Kirt starts by learning about your business and what you want to protect—whether that's a key person, ownership interest, business debt, or another financial need.
Review the Financial Impact
Together, you'll look at the financial impact the business could face and what existing resources or coverage are already available.
Compare Coverage Options
Kirt will explain the policy types, death-benefit structures, and any relevant living-benefit features that may fit the need, then compare appropriate choices from multiple insurance companies.
Apply if You Decide to Move Forward
If you choose an option, Kirt will help you through the application process. The insurance company determines final eligibility, pricing, and policy terms through underwriting.
Keep the Plan Current
As your business changes, Kirt can help review the coverage so it continues to reflect your key people, ownership, debt, and other protection needs.
Learn Before You Decide
Prefer to Learn First?
If you want to understand the options before requesting a review, start with the explanations on this page or explore the Generis Learning Center.
Business Life Basics
Learn what Business Life Insurance is and the different business needs it can help address.
Learn the BasicsPolicy Options
Understand how Term Life, Whole Life, Universal Life, and IUL may fit different business needs.
Explore Policy OptionsBusiness Life Insurance Guides
Explore guides about business loans, Key Person planning, Buy-Sell funding, and other Business Protection decisions.
Explore Business Life GuidesFrequently Asked Questions
Clear Answers Before You Decide
Business Life Insurance is life insurance used to help protect a company from financial loss tied to owners, key employees, business debt, ownership transfers, and other continuity needs. It is not one specific type of policy; the business need helps determine which coverage structure may fit.
Business owners, partners, closely held companies, professional practices, and family businesses may need Business Life Insurance when the loss of an owner or key employee, an ownership transfer, or business debt could create a financial strain. The right need depends on how the business is structured and what would be hardest to replace or fund.
It can use the same types of life insurance, but the purpose may be different. Personal coverage is generally designed to protect individuals and families, while Business Life Insurance may be used to protect a company, key people, ownership interests, business debt, or an ownership-transfer plan. Some business owners may need both personal and business coverage.
A business may own a life insurance policy in some arrangements, such as Key Person coverage. Other business protection needs may use a different owner or beneficiary. The right structure depends on the purpose of the coverage and should be coordinated with the appropriate legal and tax professionals when ownership, consent, agreements, or taxation are involved.
Key Person Insurance is life insurance designed to help a business manage the financial impact of losing an owner, executive, revenue producer, specialist, or other important person. The benefit may help provide funds for lost revenue, replacement costs, business obligations, or the time needed to stabilize operations.
Yes. Life insurance is commonly used to provide funding for an ownership transfer after an owner's death. The insurance can provide cash when it is needed, while the Buy-Sell agreement determines how the ownership transfer should occur. The agreement, business valuation, ownership structure, and tax treatment should be coordinated with the appropriate legal and tax professionals.
Term Life, Whole Life, Universal Life, and Indexed Universal Life may all be used for business protection. The appropriate type depends on how long the need may last, the amount of coverage required, budget, guarantees, flexibility, and the purpose of the policy. No single policy type is right for every business need.
Yes. Term Life can be a practical option for business needs with a defined time period, such as certain loans, temporary Key Person needs, or situations where a larger death benefit is needed at a potentially lower initial cost. Longer-term or permanent business needs may call for a different policy structure.
Not automatically. The tax treatment of Business Life Insurance depends on the purpose of the policy, who owns it, who pays the premiums, who receives the benefit, and the applicable tax rules. Business owners should review deductibility and taxation with a qualified tax professional for their specific arrangement.
Employer-owned life insurance arrangements may involve notice and consent requirements, and the rules can depend on the situation and applicable law. A business considering coverage on an employee or another key person should make sure the required consent and documentation are completed before coverage is put in place.
Potentially. Some life insurance policies include or offer living-benefit or accelerated-benefit features that may provide access to a portion of the death benefit or another rider benefit after a qualifying critical illness, chronic illness, or terminal illness. Availability, qualifying conditions, definitions, charges, and benefit amounts vary by insurer, policy, and rider. Accelerating part of a death benefit generally reduces the remaining death benefit, and the ownership and rider structure can affect who receives the benefit.
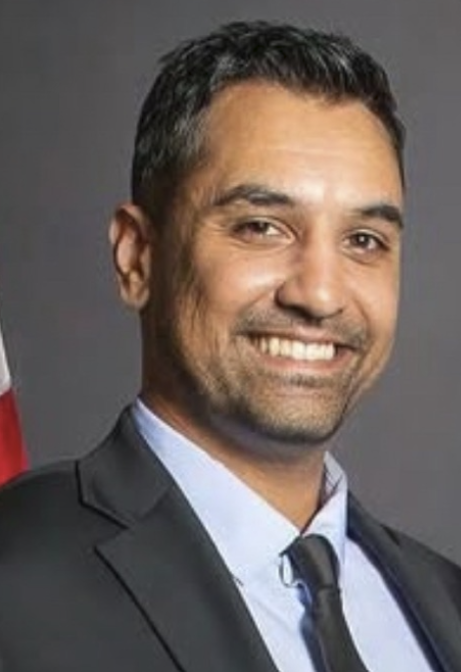
Meet Kirt Patel
Helping Business Owners Protect What They've Built
Founder of Generis Organization • Independent Life Insurance Advisor and Broker
I believe Business Life Insurance should start with understanding the business—not choosing a policy. My job is to help you identify the people, obligations, and ownership interests that may need protection, then explain the insurance options clearly.
As an independent advisor and broker, I can compare options from multiple insurance companies instead of being limited to one carrier. You'll work directly with me throughout the process, and I'll explain the tradeoffs in plain English so you can make an informed decision without pressure.
When your plan involves ownership structure, Buy-Sell agreements, business valuation, lender requirements, consent, or tax considerations, I'll help keep the insurance side coordinated with your attorney, CPA, lender, or other qualified professionals.
Compare Coverage From Trusted Insurance Companies
Carrier and product availability vary by state, strategy, underwriting, and individual circumstances.
Transparency & Licensing
Personally Licensed Across 9 States
These are the nine states where Kirt is personally licensed. Product availability, features, eligibility, underwriting, and pricing vary by state, insurer, policy, and individual circumstances.
Don't see your state?
You are still welcome to request help. If Kirt is not personally licensed where you live, Generis Organization may be able to connect you with a trusted advisor licensed in your state.
Personalized Business Protection Review
Tell Kirt What You Are Trying to Protect
Answer a few quick questions so Kirt can understand your business and what you're looking to protect before you talk.
Questions first? Call Kirt, text Kirt, schedule a consultation, or send a message.