Agreement
Sets the rules for the ownership transfer.
A Buy-Sell Agreement can determine who buys an owner's interest and under what terms. Life insurance can help answer the equally important question: where will the money come from after an owner's death or severe illness? Kirt Patel can help business owners review the funding need, compare appropriate life insurance options, and understand which policy features may fit the broader business risk.
Request My Buy-Sell Funding ReviewComplimentary Review • No Obligation • Work Directly With Kirt
Why Business Owners Trust Generis
Buy-Sell Funding Review
Share a few details and Kirt will help you understand the insurance funding side of your Buy-Sell plan before discussing coverage options.
offOr submit the short form below and Kirt will call you as soon as possible.
Prefer another way to connect? Call Kirt, text Kirt, email Kirt, or schedule a consultation.
The Agreement and the Funding
A Buy-Sell Agreement helps establish what happens to an owner's business interest after specified events. It may identify who can or must purchase the interest, how the value is determined, and how the ownership transfer should occur.
Generis Organization does not draft Buy-Sell Agreements or provide legal advice. Kirt's role is to help business owners evaluate the life insurance used to support the funding need created by the agreement.
Sets the rules for the ownership transfer.
Can provide funding for a covered death when structured to support the agreement.
Some policies may also offer benefits after a qualifying serious illness. Those features should be reviewed separately from the death-triggered ownership purchase.
The agreement sets the rules. Life insurance can provide the funding.
Liquidity When It Matters
Without readily available funding, surviving owners or the business may have to rely on available cash, borrowing, asset sales, installment payments, or another funding source at a difficult time.
Using operating cash may reduce liquidity needed for payroll, working capital, or operations.
Financing may not be available on favorable terms immediately after an owner's death.
Selling assets to raise cash may disrupt the company.
A long payout period may place continuing pressure on the business or surviving owners.
Insufficient funding may delay completion of the ownership purchase contemplated by the agreement.
The deceased owner's family or estate may be expecting payment for the ownership interest.
The Funding Process
Owners work with qualified legal counsel to establish the Buy-Sell terms.
The agreement should establish or reference an appropriate valuation method.
Determine what ownership interest may need to be purchased after an owner's death.
Determine who owns each policy, who is insured, and who receives the benefit.
Each proposed insured completes the insurer's application and underwriting requirements.
After a covered death, the named beneficiary receives policy proceeds according to the contract.
Available proceeds can help complete the ownership transfer according to the Buy-Sell Agreement.
Two Common Structures
| Comparison | Cross-Purchase | Entity-Purchase / Redemption |
|---|---|---|
| Policy owner | Other owner(s) | The business |
| Insured | Other owner(s) | Owner(s) |
| Beneficiary | Other owner(s) | The business |
| Who generally purchases the interest? | Surviving owner(s) | The business |
| Policy count | Can increase as the number of owners increases | May require fewer policies |
| Planning considerations | Ownership, basis, administration, and agreement terms should be coordinated with qualified legal and tax professionals. | Corporate ownership, valuation, estate-tax consequences, employer-owned-policy rules, and agreement terms should be coordinated with qualified legal and tax professionals. |
Neither structure is automatically better. The appropriate arrangement depends on the owners, agreement, entity structure, valuation, tax considerations, administration, and the purpose of the funding.
Avoid the Funding Gap
An agreement can be legally well designed but still be financially underfunded if the insurance does not match the purchase obligation. Kirt can help review the insurance side without drafting or interpreting the legal agreement.
Match the Funding to the Obligation
There is no universal coverage formula. The insurance should be evaluated in relation to the amount that may actually need to be paid to purchase the insured owner's interest under the agreement.
Start with the current value or valuation method established through the agreement and qualified professionals.
Consider the portion of the business that may need to be purchased after the insured owner's death.
Review how the agreement says the ownership interest should be valued without substituting insurance advice for legal interpretation.
Account for life insurance already intended to fund the ownership purchase.
Consider cash or other resources the owners and their advisors intend to use alongside insurance.
The insurer determines what amount it can financially justify based on the business and proposed arrangement.
Hypothetical Example — Not a Coverage Recommendation
A simplistic $1 million policy on every owner would not automatically match the economic obligation.
Even this simplified example is not enough to determine final coverage because the actual agreement, valuation method, entity structure, other funding sources, taxes, insurer financial underwriting, and policy ownership must also be considered.
This example is illustrative only. It is not a business valuation, legal recommendation, tax recommendation, insurance recommendation, or representation that any specific coverage amount will be available.
Funding Can Become Outdated
A Buy-Sell Agreement funded several years ago may no longer be fully funded today. Business value, ownership, debt, and available resources can change substantially over time.
Choosing the Insurance
Neither is automatically better. The appropriate design depends on how long the ownership obligation may exist, budget, guarantees, flexibility, and the agreement.
Serious Illness & Living Benefits
A serious illness can affect more than an owner's health. It may reduce their ability to work, interrupt revenue or leadership, and create financial pressure before any ownership transfer occurs.
Some life insurance policies include or offer living-benefit or accelerated-benefit features that may provide access to a portion of the death benefit—or another rider benefit—after a qualifying critical illness, chronic illness, or terminal illness.
Business pressures may include:
Different Triggers Need Different Funding
A Buy-Sell Agreement may address death, disability, retirement, termination, or other ownership-transfer events. The important point is that the funding strategy should match the specific trigger written into the agreement.
Life insurance can provide proceeds after a covered death to help fund the death-triggered ownership purchase.
Some life policies may provide access to benefits after a qualifying serious illness. These features vary by policy and are not automatically the same as a contractual disability buyout.
A disability-triggered ownership purchase may require a separate funding strategy based on the terms of the Buy-Sell Agreement.
Two Different Business Risks
| Comparison | Buy-Sell Life Insurance | Key Person Insurance |
|---|---|---|
| Primary problem | Ownership must transfer after an owner's death. | The business loses the economic contribution of an important person. |
| Money is generally intended to | Help purchase the deceased owner's ownership interest. | Help stabilize the business. |
| Coverage amount often considers | Business value, ownership percentage, agreement terms, and funding obligation. | Economic loss, replacement cost, revenue or profit contribution, obligations, and transition time. |
An owner can create both risks. The same individual may need Buy-Sell funding for the ownership-transfer obligation and separate Key Person coverage for the economic loss their death could create.
Some life policies may also offer living-benefit features that can provide additional business protection after qualifying serious illness, but those benefits should be evaluated separately from the ownership-transfer obligation.
The Key Person Insurance Calculator estimates this separate business exposure. It does not calculate the Buy-Sell ownership obligation.
Structure Matters
Ownership depends on whether the arrangement is Cross-Purchase, Entity-Purchase / Redemption, or another structure.
The beneficiary should align with the party expected to receive the insurance proceeds and fund the ownership purchase.
Employer-owned life insurance arrangements may involve written notice, consent, recordkeeping, and reporting requirements.
Tax treatment depends on the ownership, recipient, benefit type, and transaction structure. Do not assume every premium is deductible or that every death benefit or accelerated living benefit receives the same tax treatment.
Entity-Owned Insurance & Business Valuation
In the 2024 U.S. Supreme Court decision Connelly v. United States, the Court addressed the federal estate-tax valuation of a business using entity-owned life insurance to fund the redemption of a deceased owner's shares. In that case, the corporation's obligation to redeem the shares did not reduce the corporation's value for the estate-tax valuation, and the life insurance proceeds were included when determining the corporation's value before the redemption.
That does not mean Entity-Purchase or Redemption Buy-Sell arrangements are automatically inappropriate. It does mean that policy ownership, the agreement, business valuation, estate-tax exposure, and the intended ownership-transfer structure should be reviewed together rather than treating the insurance as a separate decision.
Kirt can help with the life-insurance funding side. The owners should coordinate the legal agreement, valuation, estate planning, and tax treatment with qualified legal and tax professionals.
The Review Process
Understand who owns the company and which ownership interest may need to transfer.
Identify the death-related purchase obligation and how the agreement says value should be determined.
Use the existing valuation or valuation method as the starting point for the insurance discussion.
Estimate what amount may need to be available to complete the purchase.
Account for existing life insurance and other available resources.
Review Cross-Purchase, Entity-Purchase, or another structure as established with the business's professional advisors.
Evaluate appropriate Term and Permanent choices from available insurers, including whether available living-benefit features are relevant to the broader business risk.
Kirt helps with the insurance application; the insurer determines eligibility, pricing, financial justification, and policy terms.
Review coverage as ownership, valuation, and business circumstances change.
The Generis Difference
A Buy-Sell Agreement can be carefully drafted and still have a funding gap. Kirt's role is to focus on the life insurance side—how much death-benefit funding may be needed, how the policies may be structured, whether available living-benefit features are relevant, and whether existing coverage still matches the business's current value and ownership arrangement.
Your inquiry goes directly to Kirt Patel—not a call center or rotating agent group.
Compare appropriate coverage from multiple insurance companies rather than being limited to one carrier.
Keep the insurance funding aligned with the attorney, CPA, valuation professional, lender, or other qualified professionals involved in the plan.
As ownership or business value changes, Kirt can help review whether the insurance funding still reflects the business need.
Continue Learning
Parent Service
Review how ownership funding fits alongside key people, debt, family, and continuity concerns.
Explore Business Life InsuranceEducational Resources
Continue learning about policy types and coverage decisions.
Visit the Learning CenterFrequently Asked Questions
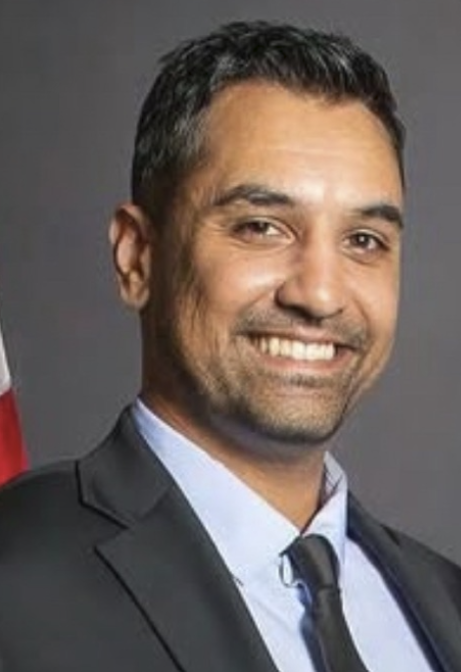
Meet Kirt Patel
Founder of Generis Organization • Independent Life Insurance Advisor and Broker
I believe Buy-Sell funding should start with the ownership obligation—not with a policy. My job is to help you understand how much life insurance may be needed, who the insurance is intended to protect, and how the funding can support the plan your business has established.
As an independent advisor and broker, I can compare coverage from multiple insurance companies instead of being limited to one carrier. We'll review the expected funding need, how long the need may exist, whether Term or Permanent coverage may fit, and whether available living-benefit features are relevant to the broader business risk.
The legal agreement, business valuation, ownership structure, basis, estate planning, and tax treatment belong with the appropriate attorneys, CPAs, valuation professionals, and other qualified advisors. I'll help keep the insurance side coordinated with those professionals when needed.
My relationship with the business does not end when a policy is issued. As the company's value, ownership, debt, or agreement changes, I'll remain available to help review whether the insurance funding still reflects the obligation you're trying to protect.
Compare Coverage From Trusted Insurance Companies
Carrier and product availability vary by state, underwriting, financial justification, policy, business, and individual circumstances.
Transparency & Licensing
Every license below can be viewed in full because transparency matters. These are the nine states where Kirt is personally licensed. Product availability, eligibility, underwriting, and pricing vary by state, insurer, policy, business, and individual circumstances.
You're still welcome to request a complimentary review. If Kirt is not personally licensed where the proposed insured owner lives, Generis Organization may be able to connect you with a trusted licensed advisor who is.
Personalized Buy-Sell Funding Review
Answer six business questions, then share your contact information. Do not include medical, banking, legal documents, or other sensitive information.
Questions first? Call Kirt, text Kirt, or send a message.