Identify the Key Person
Determine whose loss could create a meaningful financial problem.
Your business may depend heavily on an owner, executive, revenue producer, specialist, or important employee. If that person were gone, revenue, operations, client relationships, obligations, and continuity could all be affected. Kirt Patel, Founder of Generis Organization, can help identify the financial risk and compare appropriate life insurance options from multiple insurers.
Request My Key Person Protection ReviewComplimentary Review • No Obligation • Work Directly With Kirt
Why Business Owners Trust Generis
Key Person Protection Review
Share a few details and Kirt will help you identify the business risk before discussing the coverage options.
offOr submit the short form below and Kirt will call you as soon as possible.
Prefer another way to connect? Call Kirt, text Kirt, email Kirt, or schedule a consultation.
Key Person Insurance Explained
Key Person Insurance is life insurance a business obtains to help protect itself from the financial impact of losing an owner, executive, employee, or other person whose death could materially affect the company. It is also commonly called Key Man Insurance, Key Person Life Insurance, or Key Employee Insurance. These names describe the same basic business-protection purpose.
The policy does not replace the person. It can provide cash and time while the company responds to lost revenue, leadership, expertise, or relationships. Coverage should be tied to a real business exposure rather than a job title alone.
The Basic Structure
The exact arrangement depends on the business and policy, but a thoughtful Key Person plan usually follows these steps.
Determine whose loss could create a meaningful financial problem.
Review lost contribution, replacement expense, transition time, and obligations.
Determine appropriate ownership, premium payer, and beneficiary arrangements.
The proposed insured applies, provides consent, and completes insurer requirements.
The owner pays required premiums and reviews the plan as the business changes.
After a covered death, the insurer pays the named beneficiary under the policy terms.
In a classic Key Person structure, the business commonly owns the policy, pays the premium, and is the beneficiary. That is not mandatory in every situation. The arrangement should match the business purpose and applicable legal and tax requirements.
People Who May Create Business Risk
A title alone does not make someone a key person. The real question is whether losing that person would create a meaningful financial problem for the company.
Provides vision, leadership, financing relationships, or core expertise.
Contributes revenue, management, relationships, or specialized knowledge.
Directs operations, teams, strategy, or important business functions.
Produces significant revenue or manages high-value customer relationships.
Holds credentials, processes, or expertise that may be hard to replace.
Maintains important client, supplier, lender, or community connections.
Look Beyond the Job Description
A Key Person review begins with consequences. Consider what could happen before deciding how much coverage or which policy may fit.
Sales may slow, customers may leave, and new opportunities may be delayed.
Search fees, compensation, relocation, and training can require substantial cash.
Projects, approvals, leadership, and daily decisions may be interrupted.
Experience and trust built over years may not transfer quickly.
Payroll, leases, debt, and vendor commitments can continue while revenue changes.
The business may need months to recruit, transition, restructure, or recover.
The central idea: Key Person Insurance is designed to give the business financial breathing room while it responds to the loss of someone difficult to replace.
Financial Breathing Room
The named beneficiary receives the contractual benefit after a covered claim. The insurer does not wait to calculate the company's actual post-death loss. The business decides how to use available proceeds, subject to its obligations and applicable law.
Measure the Business Exposure
There is no single formula that works for every business. Compensation can be a reference point, but it may understate the economic value of someone who drives revenue, leads operations, holds customer relationships, or would take a long time to replace. Carrier financial underwriting also affects the amount available.
Uses salary, bonus, and benefits as one reference point, not a universal rule.
Estimates revenue, profit, relationships, or other value tied to the person.
Considers recruiting, transition, training, and temporary staffing costs.
Reviews obligations that could become harder to meet after the loss.
Accounts for cash reserves, existing insurance, and other business resources.
The insurer reviews whether the requested amount has reasonable financial support.
Hypothetical Example — Not a Coverage Recommendation
Those items could support reviewing a range well above a simple salary multiple. The final range should reflect documented business exposure, existing resources, and the amount an insurer can financially justify.
This example is illustrative only. It is not a carrier formula, valuation, premium quote, or statement that a particular amount will be available. Actual coverage depends on business facts, financial underwriting, medical underwriting, insurer guidelines, and policy terms.
Pricing and Underwriting
Pricing depends on the proposed insured and the coverage design. Important factors include age, health, tobacco use, coverage amount, policy type, term length, occupation, and the business's financial justification. The insurer determines eligibility and final pricing through underwriting.
No static price table can account for those variables. A comparison should use the same benefit amount and time frame while also reviewing guarantees, conversion choices, riders, and carrier strength.
Compare My Key Person OptionsChoosing a Policy Type
The expected length of the risk, budget, guarantees, flexibility, and possible long-term uses should guide the choice. Neither type is inherently better.
Compare Whole Life and Indexed Universal Life within the context of the business need.
Serious Illness Considerations
Business disruption does not always begin with death. A serious illness can interrupt leadership, productivity, revenue, and relationships. Some life insurance policies may include or offer features after a qualifying critical illness, chronic illness, or terminal illness.
Availability, definitions, triggers, waiting periods, charges, and benefits vary by insurer, policy, rider, and state. Accelerating a death benefit generally reduces the remaining death benefit. Living benefits are not the same as disability insurance and should not be presented as a replacement for disability coverage.
Different Problems, Different Funding Goals
Both may involve life insurance, but they address different business problems and should be evaluated separately.
| Comparison | Key Person Insurance | Buy-Sell Life Insurance |
|---|---|---|
| Primary problem | The business loses the economic value of a person. | Ownership must transfer under an agreement. |
| Money is generally intended to | Help stabilize the company. | Help fund the purchase of an ownership interest. |
| Coverage amount often considers | Economic business loss. | Ownership value and the agreement. |
An owner can create both risks. The business may need Key Person protection while the owners separately need Buy-Sell funding. The agreement, valuation, ownership structure, and tax treatment should be coordinated with qualified legal and tax professionals.
Ownership, Consent, and Tax Basics
In a classic arrangement, the business commonly owns the policy, pays the premium, and is the beneficiary.
The proposed insured must participate in the application and underwriting process. Employer-owned life insurance may also involve written notice, consent, and reporting requirements.
Life insurance death benefits are generally excluded from federal gross income, but employer-owned life insurance contracts have special requirements and exceptions. When the business is directly or indirectly the beneficiary, premiums generally are not deductible under federal tax rules.
The Review Process
Clarify why the person matters financially to the business.
Review contribution, replacement costs, disruption, obligations, and resources.
Determine whether the need is temporary, long-term, or expected to continue.
Review appropriate Term and Permanent choices from available insurers.
Discuss proposed-insured and financial requirements before applying.
Coordinate ownership, beneficiary, and consent details with other advisors.
Kirt helps with the application; the insurer makes the final decision.
The Generis Difference
Kirt's role is to help you define the risk, compare appropriate insurance choices, and understand the tradeoffs before you decide.
Kirt's relationship with the business does not end when a policy is issued. As key people, revenue, debt, ownership, or responsibilities change, coverage can be reviewed so the protection continues to reflect the actual business risk.
Start with the financial problem rather than a policy type.
Compare appropriate Term and Permanent options from multiple insurance companies.
Keep the insurance work aligned with your CPA, attorney, lender, and other qualified professionals when needed. Generis does not provide legal, tax, accounting, or valuation services.
Your review does not go to a call center or rotating agent group.
Learn Before You Decide
Key Person Insurance addresses one specific business risk. Review the broader parent service or continue learning about life insurance before requesting help.
Primary Related Service
See how Key Person needs can fit alongside ownership, debt, personal, and continuity concerns.
Explore Business Life InsuranceContinue Learning
Browse educational guides about policy types and coverage decisions.
Visit the Learning CenterFrequently Asked Questions
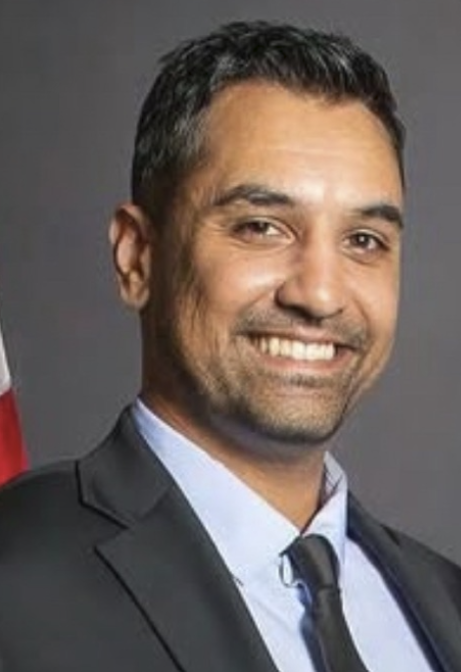
Meet Kirt Patel
Founder of Generis Organization • Independent Life Insurance Advisor and Broker
I believe business life insurance should start with understanding the financial risk—not choosing a policy. My job is to help you identify what could happen to the business if an owner, executive, revenue producer, specialist, or other key employee were suddenly no longer there, then help you understand the insurance options available.
As an independent advisor and broker, I can compare coverage from multiple insurance companies instead of being limited to one carrier. We'll look at how much protection may be appropriate, how long the need may exist, and whether Term or Permanent coverage makes the most sense for the business.
Business-owned life insurance can involve ownership, beneficiary, consent, valuation, and tax considerations. When those issues come up, I'll help keep the insurance side coordinated with your attorney, CPA, lender, or other qualified professionals.
My relationship with you doesn't end when a policy is issued. As the business grows, key people change, debt changes, or responsibilities shift, I'll remain available to help review the coverage and make sure it still reflects the risk you're trying to protect.
Compare Coverage From Trusted Insurance Companies
Carrier and product availability vary by state, underwriting, business justification, and individual circumstances.
Transparency & Licensing
Every license below can be viewed in full because transparency matters. These are the nine states where Kirt is personally licensed. Product availability, eligibility, underwriting, and pricing vary by state, insurer, policy, business, and individual circumstances.
You're still welcome to request a complimentary review. If Kirt is not personally licensed where the proposed insured lives, Generis Organization may be able to connect you with a trusted licensed advisor who is.
Personalized Key Person Review
Answer six business questions, then share your contact information. Do not include medical, banking, or other sensitive information.
Questions first? Call Kirt, text Kirt, or send a message.