Immediate Business Costs
—Replacement costs, financing needs, and other specific obligations, after subtracting insurance and resources already available.
Free educational business tool
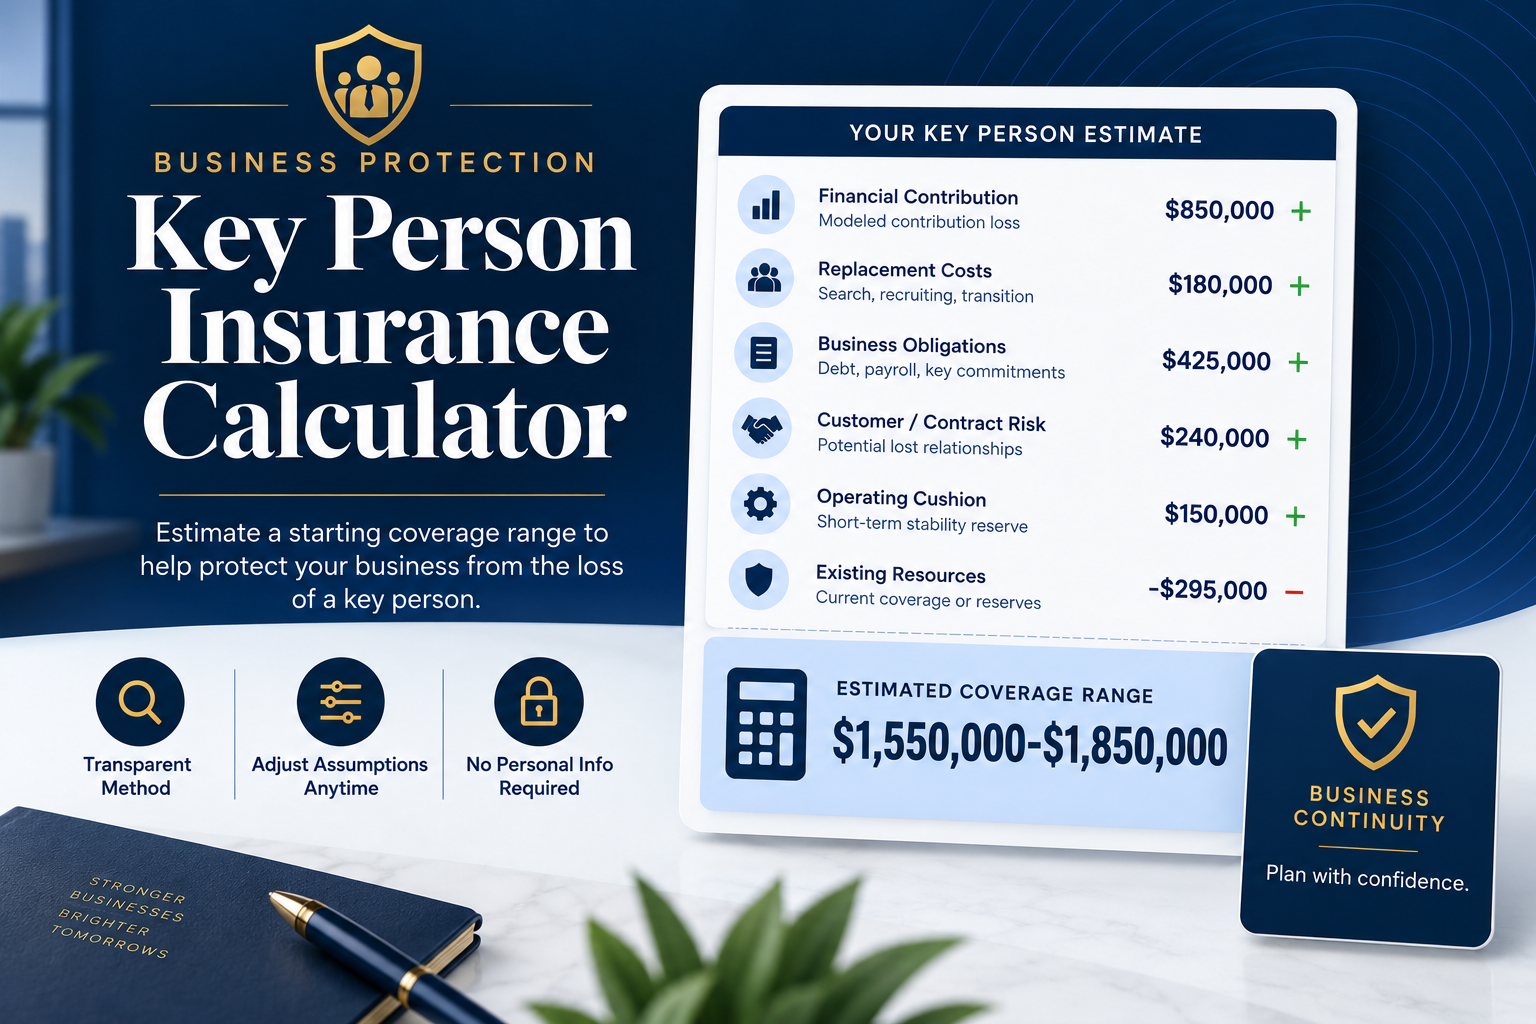
Estimate the financial impact your business could face if an important owner, executive, employee, or revenue producer were suddenly gone. See a hard-cost protection floor, a business continuity target, and a broader resilience target based on the numbers you enter.
Start with your business exposure
This calculator estimates how much money a business may want available if a key person dies or gets serious ill. It considers the financial contribution that could be lost, the time and cost to replace the person, important business obligations, and resources already available. It does not use a simple salary multiple or automatically assume all business debt should be insured.
Key Person role:
Educational planning estimate
These estimates show the immediate costs the business could face, the broader financial impact while replacing this person, and an optional extra cash cushion.
Replacement costs, financing needs, and other specific obligations, after subtracting insurance and resources already available.
Adds the estimated financial loss while the business finds, hires, and gets a replacement fully up to speed.
Adds the optional operating cash and recovery spending you chose.
Complete the core continuity assumptions to create a range.
This calculator estimates the financial impact of losing the person's contribution to the business. It does not include the separate amount that may be needed to purchase their ownership interest under a Buy-Sell Agreement. Learn about Buy-Sell Agreement life insurance.
Important: This is an educational planning estimate based on the numbers entered. It is not a business valuation, insurance quote, underwriting decision, legal or tax opinion, or guarantee that a particular amount of coverage is available. The insurance company determines eligibility, financial justification, pricing, and policy terms.
This calculator estimates Key Person business exposure. It does not calculate a Buy-Sell ownership obligation, disability buy-out funding, formal business valuation, estate-tax exposure, or the tax treatment of insurance proceeds.
Have a question about your result? Call Kirt now, or request a complimentary review below.
Kirt can review the assumptions behind your estimate, help separate Key Person exposure from Buy-Sell or other business needs, and compare available coverage options from multiple insurance companies.
Your result is already shown above. Sharing your calculator information is optional.
If you would like, you can also choose a convenient time to talk.
Book an AppointmentTransparent methodology
The calculator separates the estimate into three layers so you can see what each assumption changes. It does not use an automatic salary multiple.
Replacement and transition costs + financing exposure + critical obligations − existing dedicated resources
Essential gross need + modeled contribution disruption + additional customer loss − existing dedicated resources
Continuity gross need + operating cushion + additional stabilization cost − existing dedicated resources
When enough assumptions are known, the Continuity and Resilience estimates form the planning range. The displayed range uses the calculated amounts without automatically increasing them.
Reviewed by Kirt Patel, independent life insurance advisor and broker.
Hypothetical example
A business estimates a $240,000 annual economic contribution, 6 months to hire a replacement, 6 months ramping at 50% productivity, $60,000 of replacement and transition costs, $40,000 of critical obligations, and $50,000 of existing dedicated resources. It adds no customer or financing loss, uses $25,000 of essential monthly expenses for a 3-month cushion, and adds $0 of stabilization cost.
This is a hypothetical educational example, not a recommendation or insurance quote.
The annual economic value you estimate the person adds, entered directly or modeled from influenced revenue and contribution margin.
The expected hiring period plus the productivity shortfall while a replacement ramps up.
Recruiting, relocation, training, temporary support, retention, compensation, and other direct transition costs.
Known business obligations and financing exposure that may need funding after a loss.
An optional amount beyond the financial contribution already modeled, included only when you confirm it is not duplicated.
Essential monthly business expenses multiplied by the chosen number of cushion months.
Existing Key Person coverage, dedicated reserves, and other resources specifically available for this risk.
For a deeper explanation of coverage structure and business use, visit Key Person Insurance.
Key Person insurance protects the business from the financial impact of losing an important person. Buy-Sell funding is a separate ownership-transfer need. An owner may create both exposures, but this calculator does not calculate ownership value. Learn about Buy-Sell Agreement Life Insurance.