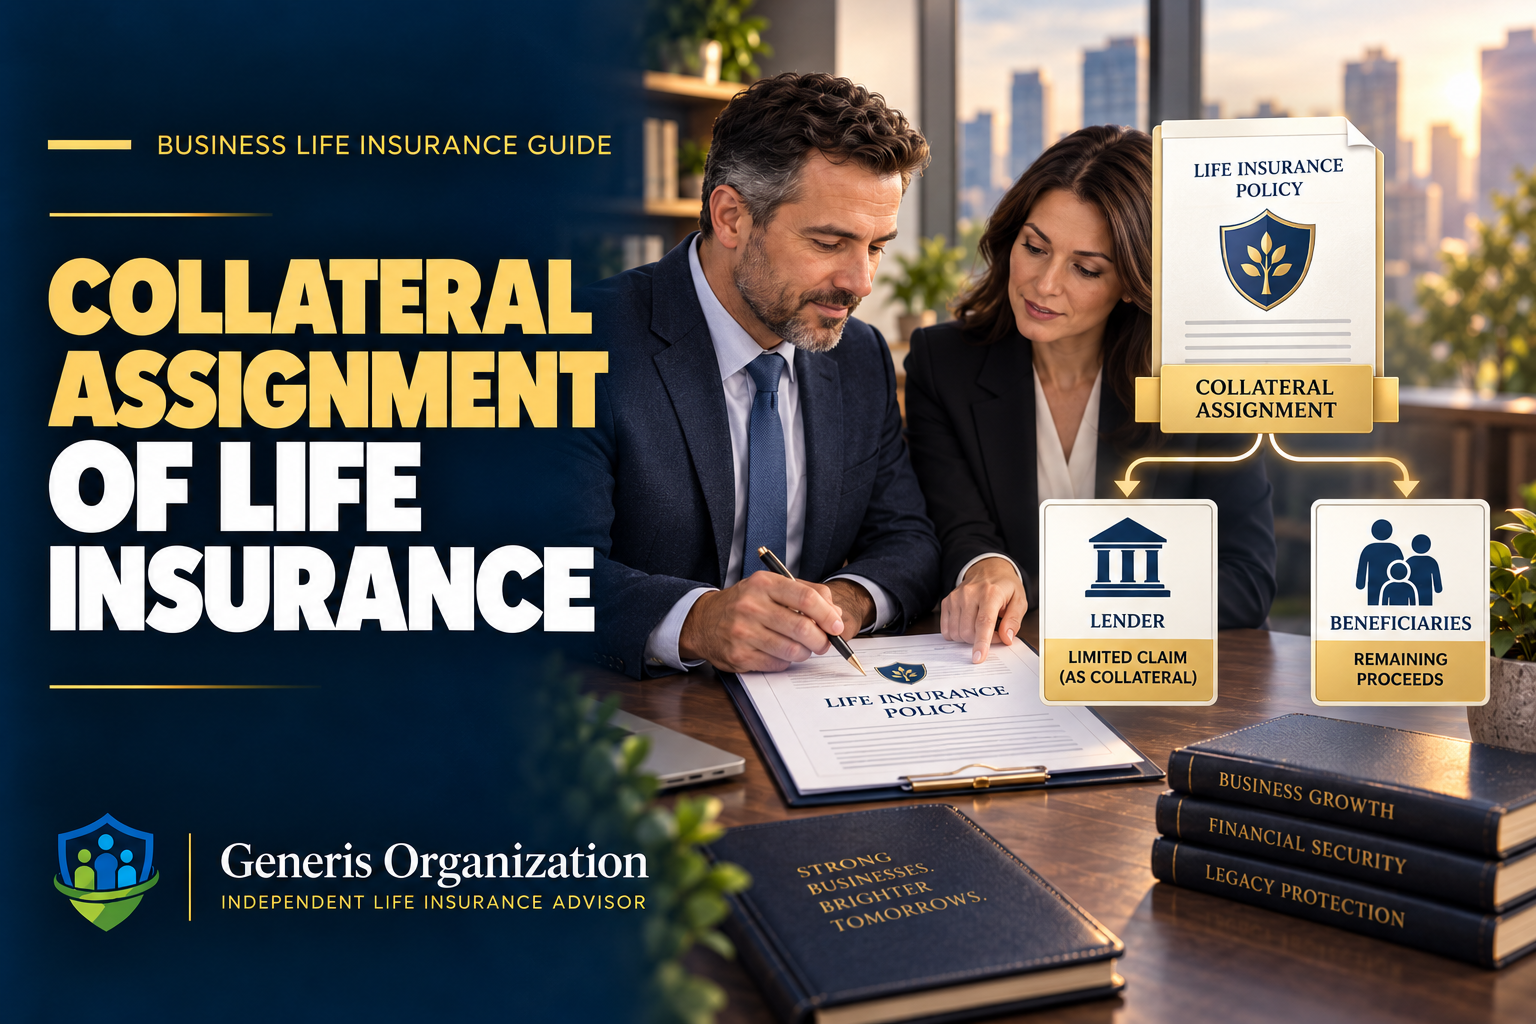
A collateral assignment gives a lender a limited financial interest in a life insurance policy as security for a loan. If the insured dies while the assignment is active, the lender is generally entitled to receive the amount it is owed under the assignment before remaining policy proceeds are paid to the policy's beneficiary, subject to the policy and assignment terms.
The lender does not automatically become the owner of the entire policy or receive the entire death benefit. The actual rights granted depend on the carrier's assignment form, the policy, the loan documents, applicable law, and any other liens or assignments.
Scope note: This guide provides general insurance education. It is not legal, tax, or lending advice and does not determine whether a specific lender will accept a policy or approve a loan. Coordinate the arrangement with the lender, insurer, and appropriate legal and tax professionals.
What Is a Collateral Assignment of Life Insurance?
A collateral assignment is a way to use rights under a life insurance policy as security for an obligation. The policy owner assigns specified rights to a lender, called the assignee. The insurer records the assignment so it can account for the lender's interest when it administers the policy or a claim.
The phrase limited interest is important, but it should not be read as identical across every form. Some carrier forms grant an assignee rights involving proceeds, surrender, loans, or policy changes. Rights reserved to the owner also vary. The signed form and policy—not a general summary—control the arrangement.
If the same policy may need to address a loan, an important person, an ownership transfer, or a family need, review each exposure separately.
How Does a Life Insurance Collateral Assignment Work?
Procedures differ by lender and insurance company, but a common sequence looks like this:
Obtain or identify an acceptable policy
The borrower or another permitted owner identifies coverage that meets the lender's and insurer's requirements. Underwriting, insurable interest, ownership, and financial justification still apply.
Complete the assignment documents
The required parties complete the carrier's collateral-assignment form and any lender documentation. The exact signatures and supporting documents vary.
The insurer records the assignment
The carrier reviews and records an acceptable assignment. A loan closing should not assume an assignment is effective before the required confirmation is received.
The lender receives the stated priority interest
While the assignment remains active, the lender has the rights described in the recorded form, subject to the policy and any superior interests.
The owner maintains the policy and loan
The borrower and policy owner continue meeting applicable premium, policy, and loan obligations. A lapse or material policy change can undermine the intended protection.
Release the assignment after repayment
After the obligation is satisfied, the lender should execute the required release and the owner should confirm the insurer's records reflect it.
Who Owns the Life Insurance Policy?
Collateral assignment is different from transferring full ownership. The policy owner may remain the owner while granting certain rights to the lender. The owner, insured, beneficiary, and assignee can be different parties.
| Role | General function | What to verify |
|---|---|---|
| Policy owner | Controls the policy except for rights limited or transferred by the assignment and policy terms. | Ownership, premium responsibility, and which actions need assignee consent. |
| Insured | The person whose death triggers the policy's death-benefit claim. | Insurable interest, underwriting, consent, and the business reason for coverage. |
| Beneficiary | Receives proceeds that remain payable under the beneficiary designation after superior policy and assignment interests are handled. | Current designation and how the assignment affects payment. |
| Assignee or lender | Receives the rights and priority interest described in the recorded assignment. | The secured obligation, amount due, notice requirements, and release process. |
Who Gets the Death Benefit?
If a covered death occurs while the assignment is active, the insurer generally determines the assignee's interest under the recorded assignment and claim documentation, then handles remaining proceeds under the policy's beneficiary designation.
In this simplified example, the lender might receive $300,000 and the designated beneficiary might receive $700,000. Actual payment depends on the amount properly owed, the assignment and policy terms, policy loans or other liens, claim review, and applicable law. The example is not a guarantee of how a particular claim will be paid.
What Happens When the Business Loan Is Paid Off?
Paying off the loan removes the underlying obligation, but an insurer's administrative record may still need a formal release. The lender typically completes a release or reassignment document, and the carrier records it according to its procedures.
The policy owner should obtain written evidence of satisfaction from the lender and confirmation from the insurance company. Do not assume every lender, carrier, or recordkeeping system releases an assignment automatically. This is also a good time to review whether the policy should remain in force for another business or family need.
Why Might a Business Lender Request Life Insurance?
A lender may consider life insurance when repayment depends heavily on a particular owner or key borrower, the debt is personally guaranteed, the business has concentrated cash-flow risk, or the lender wants additional security. The lender's credit analysis, collateral policy, loan program, and the facts of the transaction affect the decision.
Life insurance does not make a weak loan acceptable by itself and does not guarantee approval. The amount of insurance a lender will accept may also differ from the business's broader protection need.
Collateral Assignment vs. Naming the Lender as Beneficiary
A collateral assignment and a beneficiary designation are different legal and policy mechanisms. An assignment generally identifies a priority interest tied to the assigned obligation. Naming a lender as beneficiary directs death proceeds under the beneficiary designation and can produce a different result, especially if the designation does not adjust as the debt declines.
| Question | Collateral assignment | Lender named as beneficiary |
|---|---|---|
| What creates the interest? | A recorded assignment agreement. | The policy's beneficiary designation. |
| How is the lender's amount framed? | Generally by the obligation and assignment terms. | By the beneficiary designation and policy terms. |
| What may remain for others? | Remaining proceeds may pass to the designated beneficiary after the assignee's interest. | Depends on whether and how primary, contingent, or percentage beneficiaries are designated. |
Do not treat this comparison as drafting guidance. The lender, carrier, and qualified legal counsel should confirm the required structure and documents.
Collateral Assignment vs. Key Person Insurance
Collateral assignment is primarily tied to a debt obligation. Key Person Insurance is intended to help a business address economic loss caused by the death of an important owner, executive, employee, or revenue producer.
A death could create both risks, but the amounts are not interchangeable. A lender's balance does not measure lost contribution, replacement time, recruiting costs, or continuity expenses. The Key Person Insurance Calculator can organize those separate assumptions; it does not calculate a lender's legal interest or assignment amount.
Collateral Assignment vs. Buy-Sell Life Insurance
Collateral assignment supports or secures a loan. Buy-Sell Life Insurance may fund an ownership-transfer obligation after an owner's death. A business can have both needs at the same time, but one does not replace the other.
Using one policy for multiple purposes can create competing expectations about ownership, beneficiaries, coverage duration, and available proceeds. Coordinate the insurance with the loan documents and Buy-Sell Agreement rather than assuming one policy will automatically satisfy both.
Can Term Life Insurance Be Used?
Term Life Insurance may sometimes fit a defined loan period because coverage can be selected for a specified term, subject to underwriting and lender and carrier requirements. The coverage period should account for the expected obligation and the risk that repayment takes longer than planned.
Whole Life Insurance or another permanent policy may be considered when the underlying need is longer or when policy features serve a separate purpose. Indexed Universal Life is another form of permanent coverage with different funding, cost, crediting, and guarantee considerations. No policy type is universally preferable, and policy cash value should not be confused with the death benefit or with loan approval.
Collateral Assignment and SBA Loans
It is inaccurate to say that every SBA loan requires life insurance. Current requirements depend on the SBA program, loan structure, borrower and key-person circumstances, lender procedures, collateral analysis, and the version of SBA rules in effect when the loan is processed.
SBA states that SOP 50 10 contains the origination policies and procedures governing its 7(a) and 504 programs, while lenders remain responsible for applicable closing and collateral requirements. Borrowers should ask their lender which current program provision and lender policy applies to their transaction. This guide explains the insurance and collateral-assignment concept; it does not interpret loan-program eligibility or replace current SBA materials.
Questions to Review Before Assigning a Policy
- How much debt actually needs protection, and how will the amount change?
- How long is the obligation expected to remain?
- Who should own the policy and be responsible for premiums?
- Who should receive proceeds beyond the lender's interest?
- Does the coverage duration reasonably match the loan?
- What happens if the loan is refinanced, extended, or transferred?
- How will the assignment release be documented and confirmed?
- Is the same policy also intended for a Key Person, Buy-Sell, or family need?
- Which policy actions require lender consent under the actual assignment form?
- Who will review the legal, tax, lending, and insurance documents together?
What Collateral Assignment Does Not Automatically Do
- It does not necessarily transfer full policy ownership.
- It does not automatically give the lender the entire death benefit.
- It does not replace Buy-Sell planning or an ownership-transfer agreement.
- It does not replace a separate Key Person risk analysis.
- It does not guarantee loan approval or repayment.
- It does not determine the arrangement's tax treatment.
- It does not override the policy, assignment, loan documents, other superior interests, or applicable law.
When Should the Arrangement Be Reviewed?
Review the assignment after loan payoff or refinancing, a major balance change, a business ownership change, a proposed policy replacement, a beneficiary change, or a business restructuring. Also review it if premiums become difficult to maintain or the policy's performance, guarantees, or duration no longer match the obligation.
Routine review helps the parties detect a stale assignment, insufficient duration, overlapping policy purposes, or an outdated beneficiary plan before a claim or transaction makes the problem harder to correct.
Authoritative Sources and Further Reading
For current SBA program materials, see the SBA's current SOP 50 10 page and SBA lender resources. For examples of carrier-specific mechanics, review MassMutual's Collateral Assignment Form and its educational overview of life insurance as business-loan collateral. These sources illustrate why actual forms, policy terms, and current lender requirements must be reviewed; they do not establish the terms of another carrier or transaction.